Switching From Medicare Advantage to Medigap: What Arizona Retirees Should Know Before They Try
Medicare EnrollmentChoosing Medicare Advantage at 65 feels like a low-risk decision, especially with a low or zero monthly premium. The catch tends to show up years later: going from Medicare Advantage to Medigap can be much harder than getting into Medicare Advantage ever was. That’s worth knowing this fall, with Medicare’s Annual Election Period running October 15 through December 7.

Why Medicare Advantage to Medigap Is Harder Than It Looks

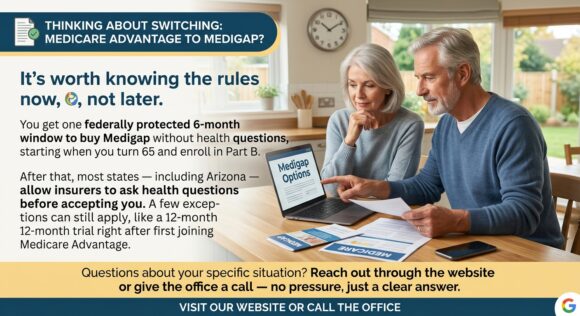
Federal law bars Medicare Advantage plans from turning you down or charging you more because of your health — you can enroll during your Initial Enrollment Period, the fall Annual Election Period, or a Special Enrollment Period, sick or not. Medigap plays by a different rulebook. You get one federally protected window, the Medigap Open Enrollment Period, which lasts six months and starts the first month you’re both 65 or older and enrolled in Medicare Part B. During those six months, any insurer selling Medigap in your state has to offer you any plan it sells, at its best available rate, regardless of your health history.

After those six months close, federal protections end and state law takes over. In most states, a Medigap insurer reviewing a later application can ask full health questions, charge a higher rate based on the answers, apply a waiting period of up to six months for a pre-existing condition, or decline the application outright.

Why 72 Is the Wrong Age to Try It

A retiree who picked a zero-premium Medicare Advantage plan at 65 often wants Medigap by 72, right around when prior authorization requirements, narrow provider networks, and out-of-network billing start to matter more. By then, a diagnosis or a longer prescription list picked up along the way can turn a simple application into a difficult one — or an impossible one, in a state without extra protections.

What Can Still Open the Door

A few situations restore your guaranteed-issue right, no matter how long it’s been:

  • The 12-month trial right. If you enrolled in Medicare Advantage when you first became eligible for Medicare, you have 12 months to drop the plan and buy any Medigap policy sold in your state without underwriting. The same 12-month right applies if you dropped a Medigap policy to try Medicare Advantage for the first time.
  • Your plan leaves the market. Guaranteed issue also kicks in if your Medicare Advantage plan exits the market, ends its contract in your service area, or you move outside the plan’s coverage area.
  • Your state’s own rules. A handful of states — Connecticut, Massachusetts, and New York among them — require Medigap insurers to issue policies year-round without underwriting. Others, including California, Oregon, and Nevada, give current Medigap policyholders an annual window, often tied to their birthday, to switch plans without health questions. Arizona is not one of the states with a birthday-rule or continuous guaranteed-issue law as of this writing.

Since Arizona doesn’t have one of these state-level protections, the federal six-month window and the situations above are what determine whether you can switch without medical underwriting here.

What to Decide Before Part B Starts

If you’re approaching 65, you’re deciding whether to use the one federally protected chance to buy Medigap on an insurer’s best terms — that decision is worth more weight than just comparing this year’s premium. If you’re already on Medicare Advantage and past your six-month window, it’s worth confirming whether a guaranteed-issue right currently applies to your situation before assuming a later switch is off the table, or assuming it’s automatically available.

Wondering whether a Medicare Advantage to Medigap switch is realistic for you? Call (623) 742-3878 for a free, no-pressure conversation — as an independent broker who doesn’t sell Medicare Advantage, I can walk through what applies to your specific timeline and situation.

This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Guaranteed-issue rules can be complex and vary by exact circumstance — confirm your specific situation with Medicare.gov, your State Health Insurance Assistance Program (SHIP), or a licensed agent before making a coverage decision.
Humana Is Dropping Medicare Advantage Plans for 2027 — What to Do If You’re Affected

Humana Medicare Advantage Arizona plan changes 2027 notice

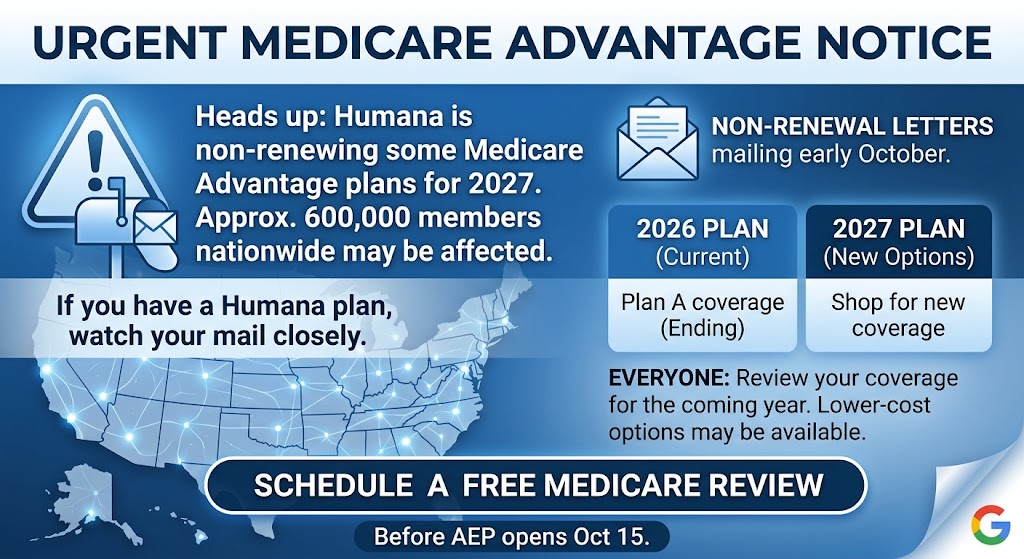
Humana has confirmed it’s exiting a number of Medicare Advantage plans for 2027, affecting roughly 600,000 members nationwide. If you have a Humana Medicare Advantage Arizona plan, this is worth paying attention to — whether or not you’ve received anything in the mail yet.

What’s actually happening

Humana is discontinuing plans it says are the “lower tail of profitability” for 2027 — mostly plans rated 3.5 stars or lower. Non-renewal letters are expected to go out starting in early October, right as Medicare’s Annual Enrollment Period opens on October 15. If your plan is affected, you’ll be notified directly by Humana, but the letter alone won’t tell you what to do next.

Why this matters even if you’re not sure you’re affected

Humana hasn’t published a full list of which specific plans or counties are impacted. The only way to know for certain is to watch your mail closely this fall — and to have a plan for what comes next if a non-renewal letter shows up. Waiting until you’re holding the letter to start comparing options means doing it under time pressure, right in the middle of AEP’s busiest weeks.

Humana Medicare Advantage Arizona: Your Options If Your Plan Is Dropped

If your Humana Medicare Advantage plan is discontinued, you’re not left without coverage — you’ll have a special enrollment window to pick something new. Depending on your situation, that could mean:

As an independent Arizona broker, I’m not tied to steering you back into another Humana Medicare Advantage Arizona product — the goal is finding whatever actually fits your coverage needs now.

What to do this fall

Whether or not you get a letter, it’s worth a quick check-in before AEP opens October 15. If you are notified that your plan is being discontinued, reach out as soon as you get the letter — the sooner we start comparing options, the less rushed the decision.

Received a non-renewal letter, or just want to make sure you’re covered either way? Call (623) 742-3878 for a free, no-pressure review.

This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare, Humana, or any government agency. Please review any notice you receive directly from your carrier for details specific to your plan.

Medicare Changes Coming in 2027: What Arizona Seniors Should Know Now

Medicare changes 2027 Arizona seniors reviewing plan options

Medicare changes 2027 Arizona seniors need to know about are here — 2027 brings some of the bigger shifts we’ve seen in a while — most of them affecting your wallet directly. Here’s what’s changing and what it means if you’re a Medicare beneficiary in Surprise, Sun City, Sun City West, or anywhere in the West Valley.

Part D costs are going up

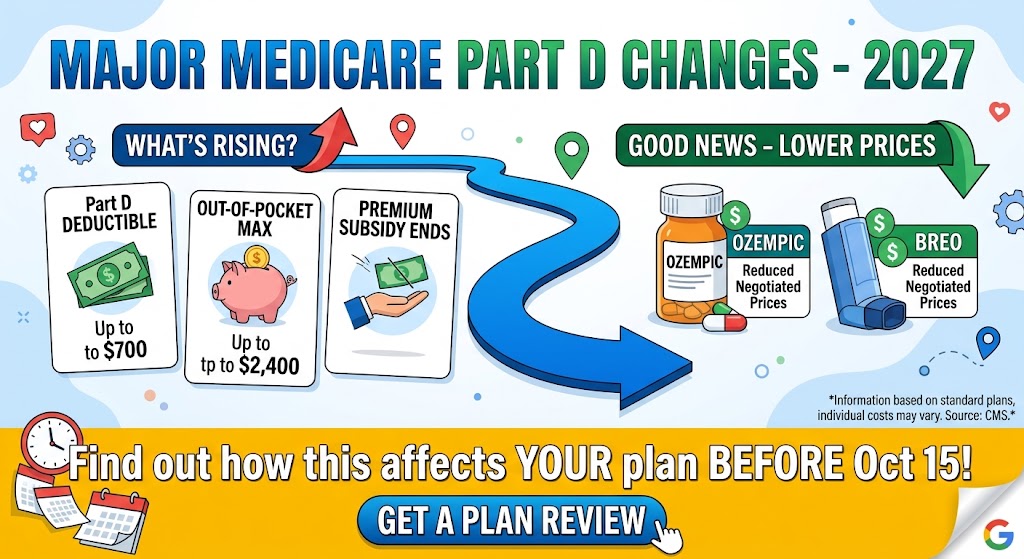
Two numbers matter here. The Part D deductible rises to $700 in 2027, up from $615 this year. And the maximum you’ll pay out of pocket for prescription drugs climbs to $2,400, up from $2,100. On top of that, a temporary subsidy that’s been softening Part D premiums by around $16 a month is set to expire, since the program funding it hasn’t been extended into 2027.

Fewer stand-alone Part D plans to choose from

If you’ve noticed your drug plan options shrinking, you’re not imagining it. Stand-alone Part D plans have dropped from around 30 options five years ago to about 11 heading into 2026 — and that trend is expected to continue. Fewer choices makes comparing what’s left even more important.

Some good news: lower prices on negotiated drugs

Medicare’s drug price negotiation program adds new savings for 2027, including notable reductions on widely used medications — Ozempic and Wegovy drop to roughly $274 (down from $959), and Breo Ellipta drops to about $67 (down from $397). If you take any of the newly negotiated drugs, this is worth checking against your current plan’s pricing.

Telehealth flexibility sticks around through 2027

Extended telehealth access, which many Medicare beneficiaries have relied on since the pandemic, has been extended through December 31, 2027, giving more time to see doctors remotely when an in-person visit isn’t necessary.

Medicare Changes 2027 Arizona: What This Means for Your Annual Enrollment Period

None of these changes take effect automatically in a way that protects you — they’re reasons to actually look at your coverage during this year’s Medicare Annual Enrollment Period, October 15 through December 7, rather than letting your plan auto-renew. A plan that made sense in 2026 may cost meaningfully more in 2027, or a competing plan may now price better for your specific medications.

Ready to see how these changes affect your specific plan? Call (623) 742-3878 for a free, no-pressure review before AEP opens.

This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Please review your Annual Notice of Change (ANOC) letter for details specific to your current plan.

Staying on top of Medicare changes 2027 Arizona seniors are facing now can save real money and hassle later. If you want help sorting through your options, give us a call.

Medicare Annual Enrollment Period 2026: What Arizona Seniors Should Do Before October 15

Every fall, Medicare’s Annual Enrollment Period (AEP) gives you a window to make changes to your coverage for the year ahead. This year, that window runs from October 15 through December 7, 2026. Any changes you make take effect January 1, 2027. Here’s what the Medicare Annual Enrollment Period Arizona season means for you this fall.

If you’re one of the many Medicare beneficiaries here in the West Valley — Surprise, Sun City, Sun City West, Peoria, and the surrounding communities — this is worth a spot on your calendar even if you’re happy with your current plan. Here’s why, and what you can actually do during this period.

What You Can Change During the Medicare Annual Enrollment Period Arizona

During the Annual Enrollment Period, you can switch from Original Medicare to a Medicare Advantage plan, or vice versa; move from one Medicare Advantage plan to another; change your Medicare Part D prescription drug plan; or enroll in a Part D plan for the first time if you didn’t sign up when you were first eligible (late enrollment penalties may apply).

One thing AEP does not cover: Medigap (Medicare Supplement) plans. Those have their own enrollment rules and typically require medical underwriting outside of your initial enrollment window.

Why review your plan even if nothing feels “wrong”

Plans change every year — provider networks, drug formularies, premiums, and extra benefits can all shift from one year to the next, even if you don’t touch a thing. A plan that was the best fit for you last January isn’t guaranteed to still be the best fit this January. A quick annual review is the only way to know for sure.

What working with an independent broker looks like

As an independent broker, I’m not tied to a single insurance company, which means the goal of our conversation is finding what actually fits your situation — not steering you toward one carrier’s product. A brief intake call to understand your current coverage, doctors, and prescriptions. Independent research across multiple carriers on your behalf. A clear, comprehensive quote emailed to you — no pressure, no obligation. You decide when (or whether) you’re ready to move forward, at your own pace.

Get Ahead of the Medicare Annual Enrollment Period Arizona Rush

AEP is a busy six weeks for everyone in this business. Reaching out before October 15 — rather than in the middle of it — usually means a more relaxed, unhurried conversation and more time to compare options carefully.

Ready to review your coverage before AEP begins? Call (623) 742-3878 or reach out through the contact form on this site, and let’s make sure your plan still fits.

This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Please review your Annual Notice of Change (ANOC) letter for details specific to your current plan.

Andy Orlikoff • NPN #7558435 • Licensed in Arizona, North Carolina & South Carolina
Verify this license at nipr.com
Follow us on Facebook
Call Now Get a Quote