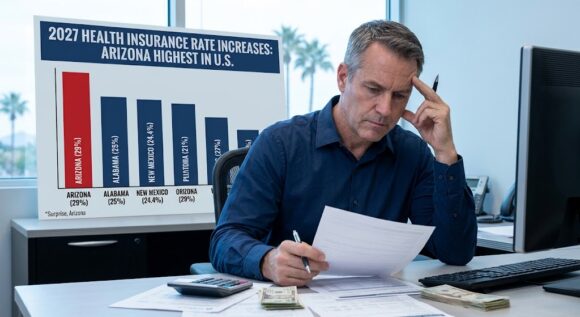
If you buy your own health insurance through the ACA marketplace, brace yourself: Arizona health insurance rates 2027 are proposed to climb by a weighted average of 29% — and according to newly filed rate data, that is the single highest proposed increase of any state in the country. Not the highest in the Southwest. The highest, period.
Arizona Health Insurance Rates 2027: How Bad Is It, Really?
For comparison, the national median proposed increase for 2027 is around 15% — already a steep number on its own. Arizona is nearly double that. Alabama comes in second-highest at 25%, followed by New Mexico at 24.4% and Kansas at 24.2%. On the other end, states like Vermont (3%), New York (6%), and Iowa (6.7%) are seeing far smaller increases. Arizona isn’t just above average — it’s the outlier at the very top of the list, and roughly 260,000 Arizonans are enrolled in ACA marketplace plans through carriers including Blue Cross Blue Shield of Arizona, UnitedHealthcare, Oscar, Health Net, and Imperial, all of whom filed rate increases as part of this proposal.
Why Arizona Got Hit This Hard
Rate filings point to the same national pressures driving up costs everywhere — rising hospital and drug costs (including a surge in demand for GLP-1 weight-loss medications), general inflation, and the expiration of enhanced federal ACA subsidies, which is expected to push healthier people out of the marketplace and leave a smaller, sicker, more expensive group of enrollees behind. Arizona’s marketplace appears to be feeling all of these pressures more acutely than most other states, which is reflected in the size of the proposed increase relative to the rest of the country.
It’s also worth noting these are proposed rates, not final ones — some states have trimmed their proposed increases significantly during regulatory review (New York’s insurers, for instance, had their 20.6% proposal cut down to 6%). Arizona’s final approved rates could move before open enrollment, but as of now, Arizona is heading into the 2027 plan year with the steepest sticker shock in the nation.
What This Means If You’re Shopping in Arizona
The good news buried in this: roughly 87% of ACA marketplace enrollees nationally qualify for subsidies, and the income thresholds for 2027 subsidy eligibility are actually rising — up to $63,840 for a single person and $132,000 for a family of four. That means a lot of Arizonans facing this 29% sticker-shock number on paper may see a much smaller real increase after subsidies are applied — but only if you actually check, rather than letting your plan auto-renew. You can check your own subsidy eligibility directly at healthcare.gov.
With a proposed increase this large, this is not the year to assume last year’s plan is still your best option. Comparing carriers and checking your updated subsidy eligibility before the marketplace’s Annual Open Enrollment period matters more in Arizona this year than almost anywhere else in the country.
Want to know what Arizona’s 29% proposed increase actually means for your specific plan and subsidy?
Free, no-pressure review — as an independent broker, I’ll walk you through your options across carriers before you’re locked into a renewal.
This article is for general educational purposes and is not a comparison of specific plans or an endorsement by the ACA marketplace, Medicare, or any government agency. Figures cited are from healthinsurance.org’s reporting on proposed 2027 rate filings (published Sept. 8, 2026, updated Sept. 25, 2026); proposed rates are subject to change during state regulatory review before final approval.
If you buy your own health insurance in Arizona, one question matters more than almost any other: do you qualify for an ACA subsidy? The answer decides whether a plan costs you a few hundred dollars a month or almost nothing — and a lot of people leave real money on the table because they assume they earn too much, or too little, to qualify. Let me clear up how it actually works.
What an ACA Subsidy in Arizona Actually Is
The subsidy — officially the premium tax credit — is money the federal government applies directly to your monthly health insurance premium when you buy a plan through the Marketplace. It lowers what you pay out of pocket each month. The amount depends mostly on your household income and household size, measured against the federal poverty level.
Here’s the part people miss: it’s not a rebate you wait for at tax time. It’s applied up front, every month, so your premium is lower from day one.
Eligibility hinges on your estimated annual household income for the coverage year, your family size, and whether you have access to affordable coverage elsewhere (like an employer plan). Because it’s based on estimated income, self-employed people and those with variable earnings have real flexibility — and real reason to get the estimate right.
Who Qualifies — and the Myth That Costs People Money
The Two Ways People Get It Wrong
I see two mistakes constantly. First, people overestimate their income out of caution and miss subsidies they’d have qualified for. Second, they underestimate and owe money back at tax time. Getting the income estimate accurate is where a broker earns their keep — it’s the difference between a pleasant surprise and an unpleasant one.
How the 2026 Rules Affect What You Pay
The enhanced premium tax credits that had removed the income cap expired at the end of 2025. For 2026, the subsidy cliff is back: the credit slides on a sliding scale up to 400% of the federal poverty level, then stops completely. That cutoff works out to roughly $62,600 for a single person and $128,600 for a family of four — earn a dollar over and the credit drops to zero. The safest move is to have your actual numbers run against this year’s brackets rather than relying on last year’s assumptions or a general rule of thumb.
Arizona Uses the Federal Marketplace
Arizona doesn’t run its own state exchange — residents enroll through the federal Marketplace at Healthcare.gov. That means the same federal subsidy rules apply here as in most states, but the plans available, their networks, and their prices are specific to Arizona and even to your county.
Two things worth knowing if you’re shopping for 2026 or 2027 coverage in Arizona specifically: Aetna exited the state’s individual market and Blue Cross Blue Shield of Arizona dropped its PPO products, which means every on-exchange plan for 2026 is HMO only — if you want PPO flexibility, you’ll need to look off-exchange. And Cigna announced in April 2026 that it’s leaving the ACA Marketplace nationwide, including Arizona, starting with the 2027 plan year. If you’re currently on a Cigna Marketplace plan, your coverage ends December 31, 2026, and you’ll need to pick a new plan for January 1.
When You Can Enroll
Most people enroll during the annual Open Enrollment Period. But if you’ve had a qualifying life event — losing other coverage, moving, marriage, a new baby, a change in income — you may qualify for a Special Enrollment Period and can enroll outside that window. Don’t assume you’ve missed your chance; it’s worth checking.
How I Help Arizona Families Get This Right
This is exactly where an independent broker saves you money and headaches. I’ll run your actual household numbers against the current subsidy brackets, show you what you truly qualify for, and compare the Arizona plans available in your county — not a generic quote. There’s no cost to you, and if a subsidized Marketplace plan is your best math, I’ll tell you; if something else fits better, I’ll tell you that too.
Looking for COBRA alternatives in Arizona? If you just lost job-based health coverage, your employer probably handed you a COBRA packet and a deadline. Before you sign it, it’s worth five minutes to see what else is actually available — because for most people, COBRA is the most expensive option on the table, not the only one.
Why COBRA Costs So Much
While you were employed, your employer was typically covering 60-80% of your premium. COBRA removes that subsidy entirely — you pay the full premium yourself, plus a 2% administrative fee. That’s why COBRA often runs $400-$700 a month for a single person, and considerably more for a family, for coverage that felt “free” or cheap while you had a job attached to it.
You have 60 days from the day your coverage ends to elect COBRA — and that same 60-day window opens up other options you may not know about.
Option 1: ACA Marketplace Plan (Usually the Strongest Option)
Losing job-based coverage triggers a Special Enrollment Period, letting you enroll in an ACA Marketplace plan right away instead of waiting for open enrollment. Marketplace plans cover the same essential health benefits as your old employer plan and can’t turn you down or charge you more for pre-existing conditions.
One important note for 2026: the enhanced premium tax credits that made Marketplace plans unusually cheap in recent years expired at the end of 2025 and were not extended. That doesn’t mean subsidies are gone — most people still qualify for some — but the numbers are different than they were a year or two ago. I’ve written a full breakdown of what changed in this post on the 2026 subsidy situation if you want the details.
Option 2: Short-Term Medical / Private PPO Plans
For healthy people bridging a gap of a few months, short-term medical plans are typically 40-60% cheaper than COBRA. The tradeoff is real, though: these plans are medically underwritten (your health history affects your rate and eligibility), they don’t have to cover the ACA’s essential health benefits, and they can deny claims tied to pre-existing conditions. Some states cap how long you can stay on one.
This is a reasonable option if you’re generally healthy and the gap is short and defined. It’s a riskier one if you have ongoing health needs — a single serious claim denial can cost far more than you saved on premium.
Option 3: A Spouse’s or Family Member’s Employer Plan
Losing your job is a qualifying life event that opens a special enrollment window on a spouse’s or parent’s employer plan, typically within 30-60 days. If that’s available to you, it’s often the cheapest and simplest option of all — worth checking before you assume COBRA or the Marketplace are your only paths.
Option 4: If You’re Near 65, COBRA May Not Be the Right Question
If you’re approaching Medicare eligibility, the calculation changes. Medicare’s Initial Enrollment Period is tied to your birthday, not your job loss, and missing it can trigger a permanent premium penalty. I’ve laid out the full timeline in this Turning 65 checklist — worth a look before you default to COBRA just because it’s the option in front of you.
Choosing Between COBRA Alternatives in Arizona
Run the real numbers before you choose anything:
Compare total cost, not just premium — factor in deductibles and how much of the year is left before they reset.
Check whether your doctors are in-network on the Marketplace or short-term plan you’re considering — COBRA keeps your old network, alternatives may not.
Weigh pre-existing conditions honestly. If you or a family member has ongoing care needs, ACA Marketplace coverage (or COBRA) protects you in a way short-term plans don’t.
Don’t let the 60-day window pass while you’re deciding — once it closes, your options narrow considerably.
Frequently Asked Questions
Why is COBRA so expensive?
While you were employed, your employer was typically covering 60-80% of your premium. COBRA removes that subsidy entirely — you pay the full premium yourself, plus a 2% administrative fee. That’s why COBRA often runs $400-$700 a month for a single person, and considerably more for a family.
How long do I have to elect COBRA coverage?
You have 60 days from the day your job-based coverage ends to elect COBRA. That same 60-day window also gives you time to compare other options, like an ACA Marketplace plan.
What’s usually the strongest alternative to COBRA?
An ACA Marketplace plan is usually the strongest option. Losing job-based coverage triggers a Special Enrollment Period, letting you enroll in a Marketplace plan right away instead of waiting for open enrollment — and Marketplace plans can’t turn you down or charge you more for pre-existing conditions.
Can I stay on a spouse’s or family member’s health plan instead of COBRA?
Losing your job is a qualifying life event that opens a special enrollment window on a spouse’s or parent’s employer plan, typically within 30-60 days. If that’s available to you, it’s often the cheapest and simplest option of all.
How I Can Help
This is exactly the kind of decision where a second opinion pays for itself. I’ll compare COBRA against ACA Marketplace and short-term options side by side, based on your actual doctors, budget, and health situation — not just the premium on the page. My help costs you nothing; you pay the same rate whether I’m involved or not.
One of the most common complaints about the ACA marketplace is that it limited health insurance choice — pushing most plans toward HMO-style networks and eliminating the flexible PPO options that many Americans preferred. However, ACA health insurance alternatives do exist for people who want more flexibility than the marketplace offers. Here’s what’s available in Arizona in 2026.
How the ACA Limited Health Insurance Choice
Before the ACA, many individuals had access to a range of private PPO plans with broad networks and no referral requirements. After 2014, most of those plans disappeared from the individual market — replaced by ACA-compliant HMO and EPO plans with narrower networks and strict in-network requirements.
The result: millions of Americans found themselves in plans that didn’t include their doctors, required referrals to see specialists, or excluded major hospitals like Mayo Clinic.
ACA Health Insurance Alternatives in Arizona
Several ACA health insurance alternatives have emerged to serve people who want more flexibility — especially those who don’t qualify for large ACA subsidies:
Off-exchange PPO plans — Available from select carriers outside the ACA marketplace. Broader networks, no referral requirements, no subsidy eligibility. Ideal for healthy individuals earning above subsidy thresholds.
Short-term medical plans — Provide PPO-style access at lower premiums. Not ACA-compliant but useful for healthy individuals between coverage periods.
Health sharing ministries — A non-insurance alternative for cost-sharing among members. Not a substitute for comprehensive coverage but used by some as a lower-cost option.
Level-funded group plans — Self-employed individuals and small business owners may qualify for group-style coverage with broader options than the individual marketplace.
Does Mayo Clinic Accept ACA Marketplace Plans?
This is one of the most important questions Arizona residents ask. Most ACA marketplace plans in Arizona do not include Mayo Clinic Arizona in their networks. Select off-exchange PPO plans do. If keeping Mayo Clinic access is a priority, this is a key reason to explore ACA health insurance alternatives.
Free Help Comparing Your Options in Arizona
I’m Andy Orlikoff, an independent health insurance broker in Surprise, AZ. I compare ACA health insurance alternatives alongside marketplace plans — showing you exactly what each option covers, what it costs, and which doctors are included. My help is free.
If you’re shopping for Arizona PPO health insurance in 2026, you’ve probably noticed two things: premiums are higher than ever, and nearly every ACA marketplace plan in Arizona is now an HMO. For many residents, that means limited doctor networks, required referrals, and no out-of-network coverage. However, there are alternatives. In this guide, you’ll see what Arizona PPO health insurance options still exist in 2026 — and how to find the right one for your situation.
Why Most 2026 ACA Plans in Arizona Are HMOs
The ACA marketplace in Arizona has shifted heavily toward HMO-style plans. As a result, most plans now require you to stay in-network, get referrals to see specialists, and forfeit coverage if you go outside the plan’s network.
For healthy individuals and families who rarely use their insurance, this structure can feel like paying a lot for very little flexibility. In addition, premiums have risen sharply in 2026 — especially for those who don’t qualify for subsidies.
Arizona PPO Health Insurance: What’s Still Available
Despite the marketplace shift, Arizona PPO health insurance options do still exist outside the ACA exchange. These include:
Off-exchange PPO plans — Available from select carriers, these plans offer broader networks and no referral requirements. However, they don’t qualify for ACA subsidies.
Short-term medical plans — These plans offer PPO-style access at significantly lower premiums. They work well for healthy individuals between jobs or waiting for open enrollment.
Level-funded group plans — Self-employed individuals and small business owners may qualify for group-style PPO coverage, often at lower cost than individual ACA plans.
Catastrophic PPO plans — Recent regulatory changes have expanded access to lower-premium, higher-deductible plans with PPO networks for qualifying individuals.
Is Arizona PPO Health Insurance Right for You?
A PPO plan makes the most sense in these situations:
You want access to Mayo Clinic or other major specialty hospitals
You see specialists regularly and don’t want referral requirements
You travel frequently and need out-of-state coverage
You earn too much to qualify for meaningful ACA subsidies
You’re generally healthy and want flexibility over comprehensive coverage
On the other hand, if you qualify for a large ACA subsidy, an HMO marketplace plan may still be the better financial choice. That’s why comparing both options side by side matters.
Mayo Clinic and Arizona PPO Plans
One of the most common questions I hear is whether a plan covers Mayo Clinic Arizona. The answer depends entirely on your plan type.
Most ACA HMO plans do not include Mayo Clinic in their networks. However, select off-exchange PPO plans do. If keeping Mayo Clinic as an option matters to you, this is one of the most important reasons to explore Arizona PPO health insurance outside the marketplace.
How Much Does Arizona PPO Health Insurance Cost in 2026?
Costs vary based on your age, household size, and the specific plan. However, as a general benchmark:
Short-term PPO plans: $100–$300/month for a healthy individual
Off-exchange PPO plans: $300–$600/month depending on coverage level
ACA HMO plans without subsidy: $450–$700+/month for comparable coverage
For many healthy Arizonans who don’t qualify for subsidies, an off-exchange or short-term PPO plan can cost significantly less while providing better network access.
Get a Free Arizona PPO Health Insurance Quote
I’m Andy Orlikoff, an independent health insurance broker based in Surprise, AZ. I’ve been helping Arizona residents compare Arizona PPO health insurance and ACA marketplace plans since 2004. I work with multiple carriers and show you both options side by side — no pressure, no commissions steering my advice.
Your premium is the same whether you use a broker or go direct. You’re just getting 20+ years of Arizona experience at no extra charge.