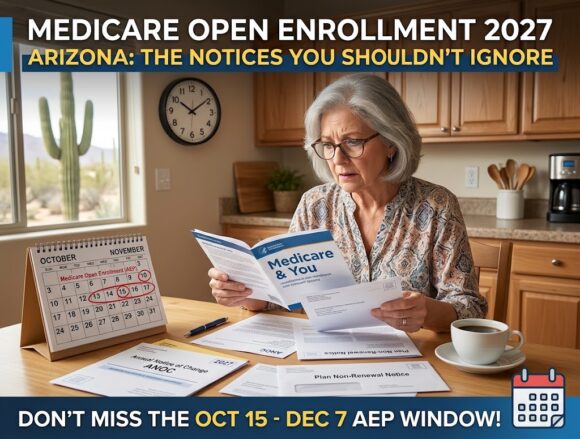
Medicare Open Enrollment 2027 Arizona officially opens October 15 and runs through December 7 — seven weeks to review your coverage and make changes for next year. But the window itself isn’t the hard part; the hard part is the stack of notices that show up beforehand, which most people skim past without realizing what each one is actually telling them.
Medicare Open Enrollment 2027 Arizona: The Notices Already in Your Mailbox
By late September, you should have received your Annual Notice of Change (ANOC) and Medicare & You handbook. The ANOC is the one worth reading closely — it spells out exactly what’s changing in your Medicare Advantage or Part D plan for 2027: copay changes, dropped providers, and medications that may no longer be covered. If a plan is leaving your county or shutting down entirely, that comes as a separate Plan Non-Renewal or Termination Notice, which can arrive at any time and opens its own special enrollment period outside the normal AEP window.
On October 14, the 2027 cost-of-living adjustment (COLA) is announced, and Medicare’s 2027 Part B premium and Part A/B deductibles follow in late October or early November. Those two numbers are what let you actually estimate next year’s costs instead of guessing. IRMAA determination letters and Social Security COLA notices follow in November and December, showing your actual 2027 premiums and any income-based surcharges.
What to Actually Check Before December 7
With the ANOC in hand, confirm three things: that your current doctors and hospitals are still in network, that your medications are still covered at the tier you expect, and that your plan’s costs still fit your budget once the new premium and deductible numbers are out. It’s also worth pulling your 2026 Medicare Summary Notices or Explanations of Benefits to check for services you didn’t actually receive — errors are more common than people assume, and AEP is a natural time to catch them.
If Something Doesn’t Add Up
If your current plan no longer fits — a doctor dropped from the network, a medication moved to a higher tier, or a cost increase that doesn’t work for your budget — Open Enrollment is your window to switch before December 7, with new coverage taking effect January 1. Setting up a my Social Security or Medicare.gov account can get these notices to you by email sooner, so you’re not relying on paper mail timing.
Not sure what your ANOC actually means for your coverage next year?
Free, no-pressure review before December 7 — I’ll help you read through the notices and compare your options.
*This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Dates and notice descriptions are from Kiplinger’s 2027 Medicare Open Enrollment guide; confirm your own plan’s specific changes directly through your ANOC or Medicare.gov.*
If you split your year between a home state and Arizona, your Medicare Advantage plan may not travel with you the way you assume. A recent case highlighted by 24/7 Wall St. makes the snowbird Medicare Advantage Arizona problem concrete: a woman who spends every February in Arizona found that while her HMO covers emergency and urgent care there, a routine, months-in-advance cardiology appointment could fall outside her plan’s network — leaving her responsible for the entire bill.
Why Snowbird Medicare Advantage Arizona Coverage Has Limits
Medicare Advantage HMOs are built around defined, often county-level service areas, and they generally require members to use in-network providers for anything routine. The exceptions are narrow: emergency care, out-of-area urgent care, and temporary out-of-area dialysis. A scheduled specialist visit — even one booked months ahead — gets no special protection just because you’re traveling. As the source article puts it, for snowbirds “geography is not a side detail. It is the product.”
The numbers make the gap obvious. For a $500 approved cardiology visit: a standard out-of-network HMO visit can cost up to the full $500, Original Medicare’s 20% coinsurance brings that down to $100, and Original Medicare paired with a Medigap Plan G can bring it to $0. Some HMO-POS plans offer partial out-of-network coverage at a higher copay, and PPOs typically include some out-of-network benefits — but at increased cost, and a standard HMO usually pays nothing at all.
What Arizona Snowbirds Should Check Before Relying on Their Plan
Prior authorization adds another layer of risk: even a willing, in-network-adjacent Arizona cardiologist can have a claim denied if the proper referral and approval weren’t secured in advance. Before booking any specialist appointment while traveling, it’s worth confirming the provider’s in-network status by name and location, not just by general reputation, and getting referrals and prior authorization paperwork in place ahead of time — not after the appointment.
It’s also worth knowing that a $0-premium Medicare Advantage plan’s out-of-pocket maximum typically applies only to in-network care — out-of-network costs can fall outside that cap entirely, which is a meaningful exposure for anyone spending real time in Arizona each year.
If You’re Considering a Change
Medicare’s Annual Election Period runs October 15 through December 7, which is the window to compare Medicare Advantage, PPO options, or Original Medicare with a Medigap supplement if your current HMO doesn’t fit your travel pattern. One important caution: if you’re thinking about leaving Medicare Advantage for Medigap, get that approval lined up first — health changes picked up during your Medicare Advantage years can make a later Medigap application harder to approve or more expensive, since most states only guarantee issue during a narrow initial window.
Splitting time between Arizona and another state? Let’s check whether your plan’s network actually covers you where you go.
Free, no-pressure review — as an independent broker who doesn’t sell Medicare Advantage, I’ll walk through what your specific travel pattern means for coverage.
*This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Figures and the case example cited are from 24/7 Wall St. reporting (Oct. 2, 2026); confirm your own plan’s network and service area directly with your carrier or Medicare.gov before making any coverage decision.*
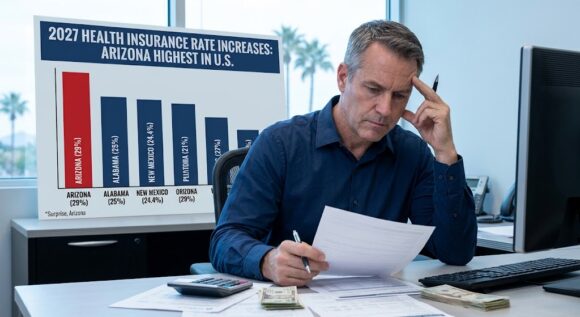
If you buy your own health insurance through the ACA marketplace, brace yourself: Arizona health insurance rates 2027 are proposed to climb by a weighted average of 29% — and according to newly filed rate data, that is the single highest proposed increase of any state in the country. Not the highest in the Southwest. The highest, period.
Arizona Health Insurance Rates 2027: How Bad Is It, Really?
For comparison, the national median proposed increase for 2027 is around 15% — already a steep number on its own. Arizona is nearly double that. Alabama comes in second-highest at 25%, followed by New Mexico at 24.4% and Kansas at 24.2%. On the other end, states like Vermont (3%), New York (6%), and Iowa (6.7%) are seeing far smaller increases. Arizona isn’t just above average — it’s the outlier at the very top of the list, and roughly 260,000 Arizonans are enrolled in ACA marketplace plans through carriers including Blue Cross Blue Shield of Arizona, UnitedHealthcare, Oscar, Health Net, and Imperial, all of whom filed rate increases as part of this proposal.
Why Arizona Got Hit This Hard
Rate filings point to the same national pressures driving up costs everywhere — rising hospital and drug costs (including a surge in demand for GLP-1 weight-loss medications), general inflation, and the expiration of enhanced federal ACA subsidies, which is expected to push healthier people out of the marketplace and leave a smaller, sicker, more expensive group of enrollees behind. Arizona’s marketplace appears to be feeling all of these pressures more acutely than most other states, which is reflected in the size of the proposed increase relative to the rest of the country.
It’s also worth noting these are proposed rates, not final ones — some states have trimmed their proposed increases significantly during regulatory review (New York’s insurers, for instance, had their 20.6% proposal cut down to 6%). Arizona’s final approved rates could move before open enrollment, but as of now, Arizona is heading into the 2027 plan year with the steepest sticker shock in the nation.
What This Means If You’re Shopping in Arizona
The good news buried in this: roughly 87% of ACA marketplace enrollees nationally qualify for subsidies, and the income thresholds for 2027 subsidy eligibility are actually rising — up to $63,840 for a single person and $132,000 for a family of four. That means a lot of Arizonans facing this 29% sticker-shock number on paper may see a much smaller real increase after subsidies are applied — but only if you actually check, rather than letting your plan auto-renew. You can check your own subsidy eligibility directly at healthcare.gov.
With a proposed increase this large, this is not the year to assume last year’s plan is still your best option. Comparing carriers and checking your updated subsidy eligibility before the marketplace’s Annual Open Enrollment period matters more in Arizona this year than almost anywhere else in the country.
Want to know what Arizona’s 29% proposed increase actually means for your specific plan and subsidy?
Free, no-pressure review — as an independent broker, I’ll walk you through your options across carriers before you’re locked into a renewal.
This article is for general educational purposes and is not a comparison of specific plans or an endorsement by the ACA marketplace, Medicare, or any government agency. Figures cited are from healthinsurance.org’s reporting on proposed 2027 rate filings (published Sept. 8, 2026, updated Sept. 25, 2026); proposed rates are subject to change during state regulatory review before final approval.
Choosing Medicare Advantage at 65 feels like a low-risk decision, especially with a low or zero monthly premium. The catch tends to show up years later: going from Medicare Advantage to Medigap can be much harder than getting into Medicare Advantage ever was. That’s worth knowing this fall, with Medicare’s Annual Election Period running October 15 through December 7.
Why Medicare Advantage to Medigap Is Harder Than It Looks
Federal law bars Medicare Advantage plans from turning you down or charging you more because of your health — you can enroll during your Initial Enrollment Period, the fall Annual Election Period, or a Special Enrollment Period, sick or not. Medigap plays by a different rulebook. You get one federally protected window, the Medigap Open Enrollment Period, which lasts six months and starts the first month you’re both 65 or older and enrolled in Medicare Part B. During those six months, any insurer selling Medigap in your state has to offer you any plan it sells, at its best available rate, regardless of your health history.
After those six months close, federal protections end and state law takes over. In most states, a Medigap insurer reviewing a later application can ask full health questions, charge a higher rate based on the answers, apply a waiting period of up to six months for a pre-existing condition, or decline the application outright.
Why 72 Is the Wrong Age to Try It
A retiree who picked a zero-premium Medicare Advantage plan at 65 often wants Medigap by 72, right around when prior authorization requirements, narrow provider networks, and out-of-network billing start to matter more. By then, a diagnosis or a longer prescription list picked up along the way can turn a simple application into a difficult one — or an impossible one, in a state without extra protections.
What Can Still Open the Door
A few situations restore your guaranteed-issue right, no matter how long it’s been:
The 12-month trial right. If you enrolled in Medicare Advantage when you first became eligible for Medicare, you have 12 months to drop the plan and buy any Medigap policy sold in your state without underwriting. The same 12-month right applies if you dropped a Medigap policy to try Medicare Advantage for the first time.
Your plan leaves the market. Guaranteed issue also kicks in if your Medicare Advantage plan exits the market, ends its contract in your service area, or you move outside the plan’s coverage area.
Your state’s own rules. A handful of states — Connecticut, Massachusetts, and New York among them — require Medigap insurers to issue policies year-round without underwriting. Others, including California, Oregon, and Nevada, give current Medigap policyholders an annual window, often tied to their birthday, to switch plans without health questions. Arizona is not one of the states with a birthday-rule or continuous guaranteed-issue law as of this writing.
Since Arizona doesn’t have one of these state-level protections, the federal six-month window and the situations above are what determine whether you can switch without medical underwriting here.
What to Decide Before Part B Starts
If you’re approaching 65, you’re deciding whether to use the one federally protected chance to buy Medigap on an insurer’s best terms — that decision is worth more weight than just comparing this year’s premium. If you’re already on Medicare Advantage and past your six-month window, it’s worth confirming whether a guaranteed-issue right currently applies to your situation before assuming a later switch is off the table, or assuming it’s automatically available.
Wondering whether a Medicare Advantage to Medigap switch is realistic for you? Call (623) 742-3878 for a free, no-pressure conversation — as an independent broker who doesn’t sell Medicare Advantage, I can walk through what applies to your specific timeline and situation.
This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Guaranteed-issue rules can be complex and vary by exact circumstance — confirm your specific situation with Medicare.gov, your State Health Insurance Assistance Program (SHIP), or a licensed agent before making a coverage decision.
If you have a Medicare Advantage plan, one of the biggest Medicare Advantage changes 2027 brings is arriving in your mailbox over the next couple of weeks. Every Medicare Advantage member with a continuing plan receives an Annual Notice of Change (ANOC) by September 30, spelling out what’s different about the plan for 2027 — and this year, more of those letters are likely to carry real changes than usual.
Why the Medicare Advantage changes 2027 brings are bigger than usual
Insurers have been pulling back from certain Medicare Advantage markets as they face rising medical costs and tighter government reimbursement. One large carrier already confirmed in late July that it’s exiting select markets for the 2027 plan year, a move expected to affect roughly 600,000 members nationwide. That follows an unusually disruptive 2026: close to 2.9 million Medicare Advantage enrollees had to find new coverage this year because their plan exited their market or was discontinued altogether — a rate about ten times the historical average.
What to actually check in your ANOC
A flat premium doesn’t mean nothing changed. Read past the monthly cost and check:
Deductibles and copays for the visits and care you actually use
Your maximum out-of-pocket limit — a modest premium bump can be dwarfed by a jump here
Whether your prescriptions are still covered, and at what tier
Whether your doctors, specialists, and preferred hospital are still in-network — plans can shrink a network even when the plan name stays the same
Extra benefits like dental, vision, hearing, or transportation, which are often the first things cut
Whether the plan still covers your county at all
If your letter says the plan is changing, it’s still available — you don’t have to switch, but it’s worth comparing against the alternatives. If instead you get a separate Plan Non-Renewal Notice, typically mailed in October, your specific plan is leaving Medicare altogether and you’ll need to pick something new before coverage ends.
The timeline ahead
By September 30: Your ANOC should arrive
October 1: 2027 plan details become public — a good time to start comparing
This is exactly the kind of yearly uncertainty that led me to stop offering Medicare Advantage altogether. With a Medicare Supplement (Medigap) plan alongside Original Medicare, your coverage isn’t tied to a shifting network or a carrier’s market decisions each fall — you get consistent rules and predictable costs, nationwide, year after year. If you’re facing a plan change or non-renewal notice this fall, that’s a good moment to see what Medigap coverage would actually look like for your situation.
Getting your ANOC and not sure what it means for you? Call (623) 742-3878 or reach out through the contact form, and as an independent Arizona health insurance broker I’ll walk through it with you — no pressure, just a clear read on your options before the December 7 deadline.
This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Please review your own Annual Notice of Change letter for details specific to your current plan.
Andy Orlikoff • NPN #7558435 • Licensed in Arizona, North Carolina & South Carolina
Verify this license at nipr.com Follow us on Facebook
 Medicare Open Enrollment 2027 Arizona officially opens October 15 and runs through December 7 — seven weeks to review your coverage and make changes for next year. But the window itself isn’t the hard part; the hard part is the stack of notices that show up beforehand, which most people skim past without realizing what each one is actually telling them.
 If you split your year between a home state and Arizona, your Medicare Advantage plan may not travel with you the way you assume. A recent case highlighted by
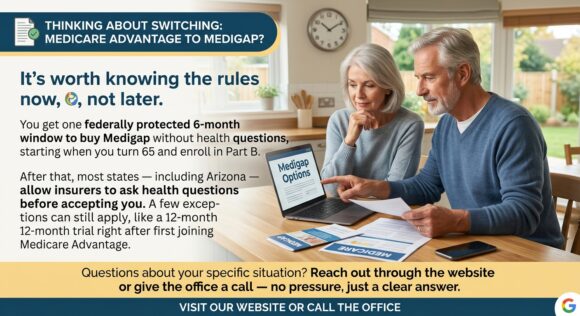 Choosing Medicare Advantage at 65 feels like a low-risk decision, especially with a low or zero monthly premium. The catch tends to show up years later: going from Medicare Advantage to Medigap can be much harder than getting into Medicare Advantage ever was. That’s worth knowing this fall, with Medicare’s Annual Election Period running October 15 through December 7.