Arizona Health Insurance Rates 2027: Highest in the U.S.
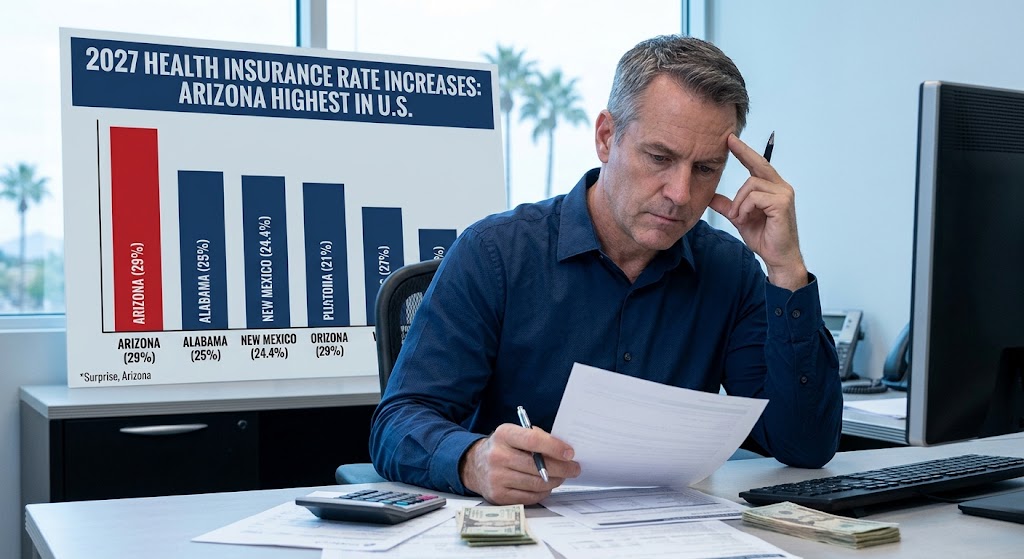
If you buy your own health insurance through the ACA marketplace, brace yourself: Arizona’s 2027 rates are final now, and the approved weighted average increase is 27.9% — the highest final increase of any state in the country. Not the highest in the Southwest. The highest, period.

These aren’t proposals anymore. The rates were approved in October, they take effect January 1, and open enrollment runs November 1 through January 15.

Arizona Health Insurance Rates 2027: How Bad Is It, Really?

Final approved increases across the country run from about 3% in Vermont up to Arizona’s 27.9%. Regulators in some states cut hard — New York’s insurers asked for 20.6% and ended at 6%. Arizona’s filings were trimmed too, just not by much. The statewide average premium jumps from $688 a month to $880 a month.

Here is each Arizona carrier’s final approved number:

  • Blue Cross Blue Shield of Arizona: 24.97% (filed at 29.59%)
  • Oscar: 33.9%
  • Imperial: 30.08%
  • Ambetter / Health Net Community Solutions: 28.0%
  • UnitedHealthcare: 28.15%
  • Health Net of Arizona: 24.1%
  • Antidote: 3.16%

And one carrier is gone entirely: Cigna is leaving Arizona’s individual market on January 1. Its roughly 2,500 members here can’t renew — they have to pick a new plan for 2027.

Roughly 260,000 Arizonans buy their coverage through the marketplace, so this lands on a lot of households.

Why Arizona Got Hit This Hard

The rate filings point to the same national pressures driving up costs everywhere — rising hospital and drug costs (including a surge in demand for GLP-1 weight-loss medications), general inflation, and the expiration of the enhanced federal ACA subsidies, which is expected to push healthier people out of the marketplace and leave a smaller, sicker, more expensive group of enrollees behind. Arizona’s marketplace is feeling all of these pressures more acutely than most other states, which is why our final number sits at the top of the list.

What This Means If You’re Shopping in Arizona

The good news buried in this: roughly 87% of ACA marketplace enrollees nationally qualify for subsidies, and the income thresholds for 2027 subsidy eligibility are actually rising — up to $63,840 for a single person and $132,000 for a family of four. That means a lot of Arizonans facing this 27.9% sticker-shock number on paper may see a much smaller real increase after subsidies are applied — but only if you actually check, rather than letting your plan auto-renew. You can check your own subsidy eligibility directly at healthcare.gov.

Two more reasons not to let this year ride. Blue Cross Blue Shield of Arizona is replacing every one of its ACA plans for 2027 — do nothing, and they pick your new plan for you. And if you’re on Cigna, there is no renewal at all. Enroll by December 15 to have coverage start January 1.

I laid out everything else that’s changing for 2027 open enrollment in Arizona here: https://azhealth.us/2026/10/2027-aca-open-enrollment-arizona/

Want to know what Arizona’s 27.9% increase actually means for your specific plan and subsidy?

📞 Call (623) 742-3878

🌐 www.azhealth.us

Free, no-pressure review — as an independent broker, I’ll walk you through your options across carriers before you’re locked into a renewal.

This article is for general educational purposes and is not a comparison of specific plans or an endorsement by the ACA marketplace, Medicare, or any government agency. Figures are Arizona’s final approved 2027 individual-market rates (approved October 2026), as tracked by healthinsurance.org. Updated October 31, 2026 — the original version of this post covered the proposed filings.
Switching From Medicare Advantage to Medigap: What Arizona Retirees Should Know Before They Try

Medicare EnrollmentChoosing Medicare Advantage at 65 feels like a low-risk decision, especially with a low or zero monthly premium. The catch tends to show up years later: going from Medicare Advantage to Medigap can be much harder than getting into Medicare Advantage ever was. That’s worth knowing this fall, with Medicare’s Annual Election Period running October 15 through December 7.

Why Medicare Advantage to Medigap Is Harder Than It Looks

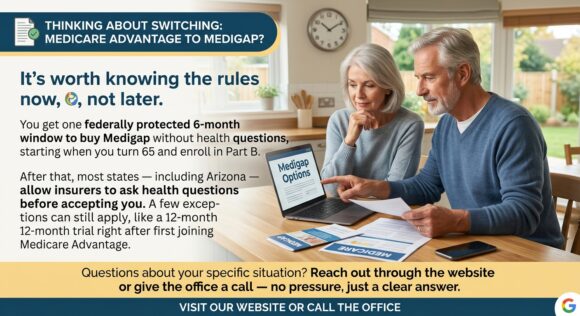
Federal law bars Medicare Advantage plans from turning you down or charging you more because of your health — you can enroll during your Initial Enrollment Period, the fall Annual Election Period, or a Special Enrollment Period, sick or not. Medigap plays by a different rulebook. You get one federally protected window, the Medigap Open Enrollment Period, which lasts six months and starts the first month you’re both 65 or older and enrolled in Medicare Part B. During those six months, any insurer selling Medigap in your state has to offer you any plan it sells, at its best available rate, regardless of your health history.

After those six months close, federal protections end and state law takes over. In most states, a Medigap insurer reviewing a later application can ask full health questions, charge a higher rate based on the answers, apply a waiting period of up to six months for a pre-existing condition, or decline the application outright.

Why 72 Is the Wrong Age to Try It

A retiree who picked a zero-premium Medicare Advantage plan at 65 often wants Medigap by 72, right around when prior authorization requirements, narrow provider networks, and out-of-network billing start to matter more. By then, a diagnosis or a longer prescription list picked up along the way can turn a simple application into a difficult one — or an impossible one, in a state without extra protections.

What Can Still Open the Door

A few situations restore your guaranteed-issue right, no matter how long it’s been:

Since Arizona doesn’t have one of these state-level protections, the federal six-month window and the situations above are what determine whether you can switch without medical underwriting here.

What to Decide Before Part B Starts

If you’re approaching 65, you’re deciding whether to use the one federally protected chance to buy Medigap on an insurer’s best terms — that decision is worth more weight than just comparing this year’s premium. If you’re already on Medicare Advantage and past your six-month window, it’s worth confirming whether a guaranteed-issue right currently applies to your situation before assuming a later switch is off the table, or assuming it’s automatically available.

Wondering whether a Medicare Advantage to Medigap switch is realistic for you? Call (623) 742-3878 for a free, no-pressure conversation — as an independent broker who doesn’t sell Medicare Advantage, I can walk through what applies to your specific timeline and situation.

This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Guaranteed-issue rules can be complex and vary by exact circumstance — confirm your specific situation with Medicare.gov, your State Health Insurance Assistance Program (SHIP), or a licensed agent before making a coverage decision.

Your Medicare Advantage Renewal Notice Is Coming: What Arizona Retirees Should Watch For This Fall

If you have a Medicare Advantage plan, one of the biggest Medicare Advantage changes 2027 brings is arriving in your mailbox over the next couple of weeks. Every Medicare Advantage member with a continuing plan receives an Annual Notice of Change (ANOC) by September 30, spelling out what’s different about the plan for 2027 — and this year, more of those letters are likely to carry real changes than usual.

Why the Medicare Advantage changes 2027 brings are bigger than usual

Insurers have been pulling back from certain Medicare Advantage markets as they face rising medical costs and tighter government reimbursement. One large carrier already confirmed in late July that it’s exiting select markets for the 2027 plan year, a move expected to affect roughly 600,000 members nationwide. That follows an unusually disruptive 2026: close to 2.9 million Medicare Advantage enrollees had to find new coverage this year because their plan exited their market or was discontinued altogether — a rate about ten times the historical average.

What to actually check in your ANOC

A flat premium doesn’t mean nothing changed. Read past the monthly cost and check:

If your letter says the plan is changing, it’s still available — you don’t have to switch, but it’s worth comparing against the alternatives. If instead you get a separate Plan Non-Renewal Notice, typically mailed in October, your specific plan is leaving Medicare altogether and you’ll need to pick something new before coverage ends.

The timeline ahead

Medicare Advantage changes 2027: why I steer clients toward Medicare Supplement instead

This is exactly the kind of yearly uncertainty that led me to stop offering Medicare Advantage altogether. With a Medicare Supplement (Medigap) plan alongside Original Medicare, your coverage isn’t tied to a shifting network or a carrier’s market decisions each fall — you get consistent rules and predictable costs, nationwide, year after year. If you’re facing a plan change or non-renewal notice this fall, that’s a good moment to see what Medigap coverage would actually look like for your situation.

Getting your ANOC and not sure what it means for you? Call (623) 742-3878 or reach out through the contact form, and as an independent Arizona health insurance broker I’ll walk through it with you — no pressure, just a clear read on your options before the December 7 deadline.

This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Please review your own Annual Notice of Change letter for details specific to your current plan.

Andy Orlikoff • NPN #7558435 • Licensed in Arizona, North Carolina & South Carolina
Verify this license at nipr.com
Follow us on Facebook
Call Now Get a Quote