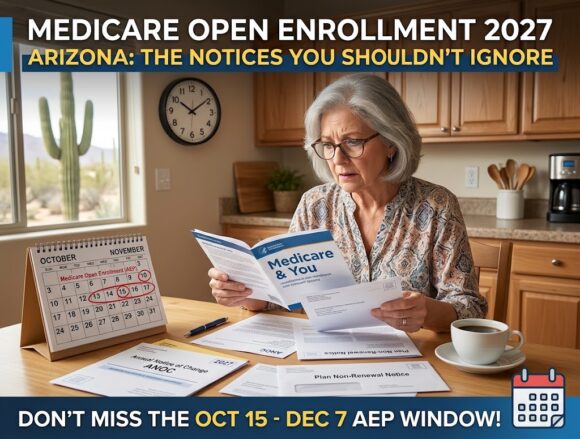
Medicare Open Enrollment 2027 Arizona officially opens October 15 and runs through December 7 — seven weeks to review your coverage and make changes for next year. But the window itself isn’t the hard part; the hard part is the stack of notices that show up beforehand, which most people skim past without realizing what each one is actually telling them.
Medicare Open Enrollment 2027 Arizona: The Notices Already in Your Mailbox
By late September, you should have received your Annual Notice of Change (ANOC) and Medicare & You handbook. The ANOC is the one worth reading closely — it spells out exactly what’s changing in your Medicare Advantage or Part D plan for 2027: copay changes, dropped providers, and medications that may no longer be covered. If a plan is leaving your county or shutting down entirely, that comes as a separate Plan Non-Renewal or Termination Notice, which can arrive at any time and opens its own special enrollment period outside the normal AEP window.
On October 14, the 2027 cost-of-living adjustment (COLA) is announced, and Medicare’s 2027 Part B premium and Part A/B deductibles follow in late October or early November. Those two numbers are what let you actually estimate next year’s costs instead of guessing. IRMAA determination letters and Social Security COLA notices follow in November and December, showing your actual 2027 premiums and any income-based surcharges.
What to Actually Check Before December 7
With the ANOC in hand, confirm three things: that your current doctors and hospitals are still in network, that your medications are still covered at the tier you expect, and that your plan’s costs still fit your budget once the new premium and deductible numbers are out. It’s also worth pulling your 2026 Medicare Summary Notices or Explanations of Benefits to check for services you didn’t actually receive — errors are more common than people assume, and AEP is a natural time to catch them.
If Something Doesn’t Add Up
If your current plan no longer fits — a doctor dropped from the network, a medication moved to a higher tier, or a cost increase that doesn’t work for your budget — Open Enrollment is your window to switch before December 7, with new coverage taking effect January 1. Setting up a my Social Security or Medicare.gov account can get these notices to you by email sooner, so you’re not relying on paper mail timing.
Not sure what your ANOC actually means for your coverage next year?
Free, no-pressure review before December 7 — I’ll help you read through the notices and compare your options.
*This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Dates and notice descriptions are from Kiplinger’s 2027 Medicare Open Enrollment guide; confirm your own plan’s specific changes directly through your ANOC or Medicare.gov.*
Medicare Part D 2027: Premiums Are Set to Rise — Here’s What Changed
Medicare Part D 2027 is shaping up differently than recent years. If you’re on a standalone Part D drug plan, there’s a real change coming worth knowing about before Open Enrollment starts this fall.
In late July 2026, the Centers for Medicare and Medicaid Services ended a program called the Part D Premium Stabilization Demonstration. That subsidy has been quietly keeping drug plan premiums low since 2025, holding the average monthly cost under $40. Without it, one federal watchdog report estimated premiums would have climbed from around $43 to about $81 a month. Now that the subsidy is gone, most experts expect standalone Part D premiums to go up for a lot of people in the new plan year — though nobody can say by exactly how much yet, since plan-specific pricing hasn’t been released.
I want to be upfront: I don’t sell standalone Part D plans, so this isn’t a pitch. But I talk to a lot of people every year who assume their Medicare coverage just renews itself the same way, year after year, and this is exactly the kind of change that makes assuming a bad idea.
What Actually Happens Next
Your Part D carrier will send you an Annual Notice of Change (ANOC) this fall. That letter spells out exactly what’s changing about your specific plan — premium, deductible, drug formulary, all of it. Don’t let it sit in a pile of mail.
Then you’ve got a real window to act. Medicare Open Enrollment runs October 15 through December 7. That’s your chance to compare Part D plans, switch if your current one got more expensive, or just confirm what you have still makes sense heading into Medicare Part D 2027.
While You’re Looking, Look at the Whole Picture
Medicare Part D 2027 pricing changes are a good excuse to actually sit down and look at your full Medicare setup, not just the drug plan. That includes your Medicare Supplement coverage — is it still the right fit, still priced competitively, still covering what you need? A lot of people haven’t checked in years.
If you want a second set of eyes on any of it — your Part D options, your Supplement plan, or just want someone to walk through what Open Enrollment actually means for your situation — give me a call or visit the website. No pressure, no call center, just a real conversation about what makes sense for you.
Here’s something most people don’t realize: you can switch Medicare Supplement plans in Arizona almost any month of the year — you’re not locked in. But “you can apply” and “you’ll get approved at a good rate” are two very different things, and the difference comes down to timing and your health. Let me walk you through how it actually works, because the rules aren’t what most people assume.
You Can Switch Medicare Supplement Plans in Arizona Anytime
Unlike Medicare Advantage, which locks you into set enrollment periods, Medigap plans have no annual “open enrollment” for switching. You can submit an application to change carriers or plans in January, July, or any month you like.
The catch is that outside of your protected windows, switching usually means going through medical underwriting — the insurance company reviews your health history and can charge you more, add exclusions, or decline you outright.
The One Window Where Health Doesn’t Matter
There’s a golden period when you can buy or switch to almost any Medigap plan with no medical underwriting at all: your Medigap Open Enrollment Period. This is the six-month window that starts the month you’re 65 or older and enrolled in Medicare Part B. During those six months, carriers must sell you a policy at their best rate regardless of your health.
If you’re in that window right now, this is the single best time to get the coverage you want. Miss it, and the rules change — which is exactly why timing matters so much.
Guaranteed Issue Rights: Switching Without Underwriting
Even outside that first six months, certain life events give you guaranteed issue rights — the right to buy specific Medigap plans without underwriting. These situations include:
Losing employer or group coverage — when the employer-sponsored, COBRA, or retiree coverage that pays after Medicare comes to an end.
Your Medicare Advantage plan leaving — if your MA plan discontinues in your area, shrinks its service area, or its contract terminates.
Trial rights — if you tried Medicare Advantage when you first became eligible (or dropped a Medigap policy to try MA) and switch back to Original Medicare within 12 months.
Your Medigap carrier failing — if your insurer goes bankrupt, ends coverage through no fault of yours, or misled you.
Moving out of your plan’s service area — for an MA or Medicare SELECT plan.
This is where a lot of Arizona retirees — and younger beneficiaries — leave money on the table. They assume they’re stuck, when a recent change in their situation actually opened a no-underwriting door. But that door closes fast: you generally have no more than 63 days after your prior coverage ends to use a guaranteed-issue right. In many cases you can even apply up to 60 days before the coverage ends, so acting early is smart.
One important note for Arizona specifically: unlike some states, Arizona does not offer an additional guaranteed-issue protection for under-65 Medicare beneficiaries who qualify by disability. If that’s your situation, it’s worth a call before you assume a switch is straightforward — your options and timing will look different, and I can walk you through what’s actually available.
Why People Switch in the First Place
The most common reason isn’t dissatisfaction with coverage — since all Medigap plans of the same letter are standardized by law, a Plan G from one carrier covers exactly what a Plan G from another does. The real driver is price. Carriers raise rates over time, and the company that was cheapest when you enrolled may not be cheapest three years later.
Because the benefits are identical, moving to a lower-priced carrier for the same plan letter is often pure savings — you keep the exact coverage and pay less for it.
What Switching Actually Involves
The process is more straightforward than people fear:
You apply with the new carrier and go through underwriting (unless you’re in a protected window).
You don’t cancel your old policy until the new one is approved and active — never leave yourself with a gap.
Once the new plan is confirmed, you cancel the old one, and you’re done.
The mistake I see most often is people canceling first out of eagerness, then getting declined by the new carrier and scrambling. Approval first, always.
How I Help Arizona Clients Decide
This is exactly the kind of situation where an independent broker earns their keep. I’m contracted with multiple carriers across Arizona, so I can check whether a switch actually saves you money for the same standardized coverage — and whether your timing puts you in a protected window or means underwriting. There’s no cost to you, and I never push a switch that doesn’t benefit you.
If you’re wondering whether you’re overpaying, or whether a recent life change opened a no-underwriting window, it’s worth a quick conversation before that window closes.
Medicare AEP 2026 Arizona — the Annual Enrollment Period — runs October 15 through December 7, 2026. Any changes you make take effect January 1, 2027. Here’s what Medicare AEP 2026 actually covers, what’s new for 2026, and why it’s worth a look even if you’re not planning to change anything.
What Medicare AEP 2026 Arizona Actually Covers
AEP is specifically the window for changing Medicare Advantage and Part D prescription drug coverage — joining, switching, or dropping either. It is not the enrollment window for Medicare Supplement (Medigap) plans. Medigap doesn’t have a single national enrollment period the way Advantage and Part D do; you can generally shop for a Medigap plan at any time, though outside your original Medigap Open Enrollment window or a guaranteed-issue situation, carriers can medically underwrite you.
Why Medicare AEP 2026 Arizona Still Matters for Medigap Holders
Even though Medigap itself isn’t on the AEP calendar, fall is still the right time to check a few things:
Your Part D drug plan — if you carry a standalone Part D plan alongside Medigap, its formulary and pricing can change every year, so it’s worth reviewing during AEP (I’m not licensed to sell Part D plans myself, but it’s still worth checking on your end or with your Part D agent).
Your Medigap premium — carriers commonly adjust Medigap rates at renewal. If yours went up significantly, it’s worth comparing what else is available, especially if your health has stayed steady since you first enrolled.
Whether Medicare Advantage still makes sense for you — if you’re on an Advantage plan and considering a move to Original Medicare plus Medigap, AEP is when you’d drop the Advantage plan; just know that moving to Medigap afterward may involve medical underwriting unless you qualify for guaranteed issue.
Medicare AEP 2026 Arizona: What’s New This Year
A few concrete numbers worth knowing this year:
According to SSA.gov, the standard Medicare Part B premium is $202.90/month for 2026, up from $185/month in 2025.
The Part D out-of-pocket cap increased from $2,000 (2025) to a higher indexed amount for 2026, and enrollees can still choose to spread that cost across the year in equal monthly payments instead of paying it early.
Some insurers are exiting the Medicare Advantage market or reducing plan offerings for 2026 — if that affects your current plan, you’ll likely get a notice from your carrier this fall, and it’s worth acting on it rather than setting it aside.
A Few Common Mistakes During AEP
Comparing plans on premium alone, without confirming your doctors and pharmacy are still in-network. Waiting until the first week of December to make a decision, which leaves little room to fix a mistake before the deadline. Assuming a plan that worked well last year hasn’t changed — formularies and networks are re-evaluated annually, not locked in.
How I Can Help
When you call, I spend about five minutes learning your situation, then I go research quotes across multiple Medigap carriers — not just one company’s price. You get a detailed, side-by-side quote by email, and you review it on your own time. No pressure to decide on the call. I don’t sell Medicare Advantage or Part D plans, so I’m not working an angle when I tell you whether your current Medigap setup still makes sense or not.
I’ve laid out the full turning-65 process in this Medicare checklist, and if Mayo Clinic access matters to your plan choice, I’ve covered exactly which plans keep it in-network in this breakdown.
Frequently Asked Questions
What are the AEP dates for 2026?
Medicare’s Annual Enrollment Period runs October 15 through December 7, 2026. Changes made during this window take effect January 1, 2027.
Does AEP apply to Medicare Supplement (Medigap) plans?
No. AEP covers Medicare Advantage and Part D prescription drug plan changes. Medigap doesn’t have a fixed annual enrollment period — you can generally apply anytime, though medical underwriting may apply outside your original Medigap Open Enrollment window or a guaranteed-issue situation.
What is the Medicare Part B premium for 2026?
The standard Part B premium for 2026 is $202.90 per month, up from $185 per month in 2025. Higher-income enrollees pay more.
What happens if I miss the December 7 AEP deadline?
If you miss AEP and don’t qualify for a Special Enrollment Period, you’ll generally need to wait for the Medicare Advantage Open Enrollment Period (January 1 – March 31), which has more limited options — it only allows switching between Medicare Advantage plans or dropping Advantage for Original Medicare, not adding or changing a standalone Part D plan.
Mayo Clinic Arizona insurance questions come up constantly — Mayo in Scottsdale and Phoenix is one of the top reasons people choose to stay in Arizona for their healthcare. But here’s what a lot of people don’t find out until they’re already sitting in the waiting room with the wrong coverage: not every health plan gets you in the door. Here’s exactly what does — and doesn’t — work.
Mayo Clinic Arizona Insurance: The Short Answer
Original Medicare + a Medicare Supplement (Medigap) — accepted at Mayo Clinic Arizona, no exceptions.
Medicare Advantage — Mayo Clinic does not accept non-contracted Medicare Advantage plans. If you’re on one, don’t assume you’re covered.
ACA Marketplace plans (Ambetter, Blue Cross Blue Shield, Cigna, Oscar, UnitedHealthcare Marketplace) — not accepted at Mayo Clinic Arizona as of 2026.
Private off-exchange PPO plans (like UHC Choice Plus or Aetna Open Choice PPO) — accepted, but these are underwritten plans you buy directly, not subsidized Marketplace plans.
If You’re on Medicare: The Plan G vs. Plan N Detail That Matters at Mayo
Mayo Clinic Arizona accepts Original Medicare and any Medicare Supplement carrier — that part is straightforward. But there’s a detail specific to the Arizona location that trips people up: unlike Mayo’s Florida campus, Mayo Clinic Arizona does not accept full Medicare Assignment. That means they’re allowed to bill up to 15% above what Medicare approves — what’s called an “excess charge.”
This is exactly where the choice between Medigap Plan G and Plan N actually matters. Plan G covers those excess charges in full. Plan N does not — so if you’re a Plan N holder being treated at Mayo Clinic Arizona, you could see a bill for that difference. I’ve written a full breakdown of Plan G vs. Plan N in Arizona if you want the complete comparison, but if Mayo Clinic access matters to you specifically, that excess-charge detail alone is often reason enough to choose Plan G.
You’ll also need a referral to be seen at Mayo, and in some cases prior authorization for specific tests or procedures — standard Medicare rules, not something unique to Mayo.
Why Medicare Advantage Is the Riskiest Choice Here
Mayo Clinic’s own guidance is direct: they do not accept non-contracted Medicare Advantage plans. If you’re 65+ and want reliable access to Mayo, a Medicare Advantage plan puts that access at the mercy of whatever network your specific carrier has negotiated — and that can change year to year. I don’t sell Medicare Advantage, and this is one of the clearest real-world examples of why: here’s the full explanation.
If You’re Under 65: The ACA Marketplace Doesn’t Get You In
This is the one that catches people off guard. None of the individual ACA Marketplace plans sold in Arizona for 2026 — not Ambetter, not Blue Cross Blue Shield, not Cigna, not Oscar, not UnitedHealthcare’s Marketplace plans — are accepted at Mayo Clinic Arizona. Banner|Aetna and BCBS Statewide PPO, which used to offer some access, are no longer on the ACA Marketplace at all as of 2026.
To get Mayo Clinic access under 65, you generally need a private, off-exchange PPO plan — options like UHC Choice Plus or Aetna’s Open Choice PPO network are commonly accepted. These aren’t Marketplace plans, so there’s no subsidy, and most are medically underwritten, meaning your health history affects your rate and whether you qualify at all. That’s a real tradeoff: broader network access in exchange for underwriting and no tax credit.
Frequently Asked Questions
Does Mayo Clinic Arizona accept Medicare?
Yes — Original Medicare plus a Medicare Supplement (Medigap) is accepted at Mayo Clinic Arizona with no exceptions.
Does Mayo Clinic Arizona accept Medicare Advantage plans?
Mayo Clinic does not accept non-contracted Medicare Advantage plans. If you’re on a Medicare Advantage plan, don’t assume you’re covered — check your specific plan’s contract status before you need care.
Does Mayo Clinic Arizona accept ACA Marketplace plans?
No. As of 2026, ACA Marketplace plans — including Ambetter, Blue Cross Blue Shield, Cigna, Oscar, and UnitedHealthcare Marketplace — are not accepted at Mayo Clinic Arizona.
What insurance do I need to see a doctor at Mayo Clinic Arizona if I’m under 65?
Private off-exchange PPO plans, such as UHC Choice Plus or Aetna Open Choice PPO, are accepted at Mayo Clinic Arizona. These are medically underwritten plans purchased outside the ACA Marketplace.
How I Can Help
Whether Mayo Clinic access is the deciding factor for you or just one piece of a bigger decision, I’ll compare your options — Medigap, ACA Marketplace, or private PPO — against what you actually need, including which hospitals and doctors matter to you. I don’t sell Medicare Advantage, and I’ll tell you plainly when a plan won’t get you where you want to go.
Serving Scottsdale, Phoenix, Surprise, Peoria, Glendale, Mesa, Chandler, Gilbert, and all of Arizona.
American Insurance Benefits | 14955 W Bell Rd #8031, Surprise, AZ 85374 | Licensed Arizona Insurance Broker since 1999. This page reflects Mayo Clinic Arizona’s publicly stated insurance policies as of 2026; always confirm current network status directly with Mayo Clinic before making a coverage decision.
Andy Orlikoff • NPN #7558435 • Licensed in Arizona, North Carolina & South Carolina
Verify this license at nipr.com Follow us on Facebook
 Medicare Open Enrollment 2027 Arizona officially opens October 15 and runs through December 7 — seven weeks to review your coverage and make changes for next year. But the window itself isn’t the hard part; the hard part is the stack of notices that show up beforehand, which most people skim past without realizing what each one is actually telling them.