Medicare changes 2027 Arizona seniors need to know about are here — 2027 brings some of the bigger shifts we’ve seen in a while — most of them affecting your wallet directly. Here’s what’s changing and what it means if you’re a Medicare beneficiary in Surprise, Sun City, Sun City West, or anywhere in the West Valley.
Part D costs are going up
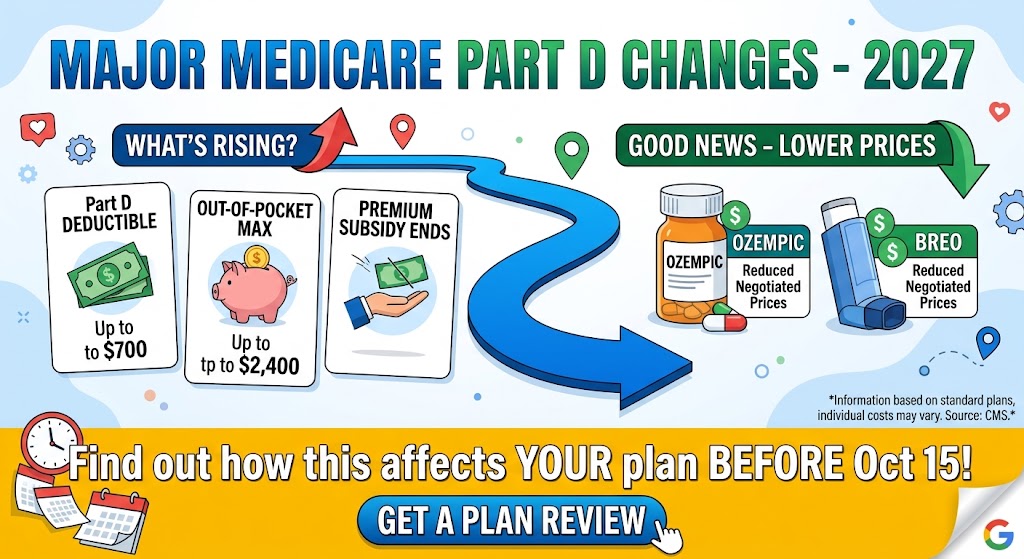
Two numbers matter here. The Part D deductible rises to $700 in 2027, up from $615 this year. And the maximum you’ll pay out of pocket for prescription drugs climbs to $2,400, up from $2,100. On top of that, a temporary subsidy that’s been softening Part D premiums by around $16 a month is set to expire, since the program funding it hasn’t been extended into 2027.
Fewer stand-alone Part D plans to choose from
If you’ve noticed your drug plan options shrinking, you’re not imagining it. Stand-alone Part D plans have dropped from around 30 options five years ago to about 11 heading into 2026 — and that trend is expected to continue. Fewer choices makes comparing what’s left even more important.
Some good news: lower prices on negotiated drugs
Medicare’s drug price negotiation program adds new savings for 2027, including notable reductions on widely used medications — Ozempic and Wegovy drop to roughly $274 (down from $959), and Breo Ellipta drops to about $67 (down from $397). If you take any of the newly negotiated drugs, this is worth checking against your current plan’s pricing.
Telehealth flexibility sticks around through 2027
Extended telehealth access, which many Medicare beneficiaries have relied on since the pandemic, has been extended through December 31, 2027, giving more time to see doctors remotely when an in-person visit isn’t necessary.
Medicare Changes 2027 Arizona: What This Means for Your Annual Enrollment Period
None of these changes take effect automatically in a way that protects you — they’re reasons to actually look at your coverage during this year’s Medicare Annual Enrollment Period, October 15 through December 7, rather than letting your plan auto-renew. A plan that made sense in 2026 may cost meaningfully more in 2027, or a competing plan may now price better for your specific medications.
Ready to see how these changes affect your specific plan? Call (623) 742-3878 for a free, no-pressure review before AEP opens. As an independent Arizona health insurance broker, I can also show you how a Medicare Supplement plan compares with staying on Medicare Advantage.
This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Please review your Annual Notice of Change (ANOC) letter for details specific to your current plan.
Staying on top of Medicare changes 2027 Arizona seniors are facing now can save real money and hassle later. If you want help sorting through your options, give us a call.
Every fall, Medicare’s Annual Enrollment Period (AEP) gives you a window to make changes to your coverage for the year ahead. This year, that window runs from October 15 through December 7, 2026. Any changes you make take effect January 1, 2027. Here’s what the Medicare Annual Enrollment Period Arizona season means for you this fall.
If you’re one of the many Medicare beneficiaries here in the West Valley — Surprise, Sun City, Sun City West, Peoria, and the surrounding communities — this is worth a spot on your calendar even if you’re happy with your current plan. Here’s why, and what you can actually do during this period.
What You Can Change During the Medicare Annual Enrollment Period Arizona
During the Annual Enrollment Period, you can switch from Original Medicare to a Medicare Advantage plan, or vice versa; move from one Medicare Advantage plan to another; change your Medicare Part D prescription drug plan; or enroll in a Part D plan for the first time if you didn’t sign up when you were first eligible (late enrollment penalties may apply).
One thing AEP does not cover: Medigap (Medicare Supplement) plans. Those have their own enrollment rules and typically require medical underwriting outside of your initial enrollment window.
Why review your plan even if nothing feels “wrong”
Plans change every year — provider networks, drug formularies, premiums, and extra benefits can all shift from one year to the next, even if you don’t touch a thing. A plan that was the best fit for you last January isn’t guaranteed to still be the best fit this January. A quick annual review is the only way to know for sure.
What working with an independent broker looks like
As an independent broker, I’m not tied to a single insurance company, which means the goal of our conversation is finding what actually fits your situation — not steering you toward one carrier’s product. A brief intake call to understand your current coverage, doctors, and prescriptions. Independent research across multiple carriers on your behalf. A clear, comprehensive quote emailed to you — no pressure, no obligation. You decide when (or whether) you’re ready to move forward, at your own pace.
Get Ahead of the Medicare Annual Enrollment Period Arizona Rush
AEP is a busy six weeks for everyone in this business. Reaching out before October 15 — rather than in the middle of it — usually means a more relaxed, unhurried conversation and more time to compare options carefully.
Ready to review your coverage before AEP begins? Call (623) 742-3878 or reach out through the contact form on this site, and let’s make sure your plan still fits.
This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Please review your Annual Notice of Change (ANOC) letter for details specific to your current plan.
Medicare Part D 2027: Premiums Are Set to Rise — Here’s What Changed
Medicare Part D 2027 is shaping up differently than recent years. If you’re on a standalone Part D drug plan, there’s a real change coming worth knowing about before Open Enrollment starts this fall.
In late July 2026, the Centers for Medicare and Medicaid Services ended a program called the Part D Premium Stabilization Demonstration. That subsidy has been quietly keeping drug plan premiums low since 2025, holding the average monthly cost under $40. Without it, one federal watchdog report estimated premiums would have climbed from around $43 to about $81 a month. Now that the subsidy is gone, most experts expect standalone Part D premiums to go up for a lot of people in the new plan year — though nobody can say by exactly how much yet, since plan-specific pricing hasn’t been released.
I want to be upfront: I don’t sell standalone Part D plans, so this isn’t a pitch. But I talk to a lot of people every year who assume their Medicare coverage just renews itself the same way, year after year, and this is exactly the kind of change that makes assuming a bad idea.
What Actually Happens Next
Your Part D carrier will send you an Annual Notice of Change (ANOC) this fall. That letter spells out exactly what’s changing about your specific plan — premium, deductible, drug formulary, all of it. Don’t let it sit in a pile of mail.
Then you’ve got a real window to act. Medicare Open Enrollment runs October 15 through December 7. That’s your chance to compare Part D plans, switch if your current one got more expensive, or just confirm what you have still makes sense heading into Medicare Part D 2027.
While You’re Looking, Look at the Whole Picture
Medicare Part D 2027 pricing changes are a good excuse to actually sit down and look at your full Medicare setup, not just the drug plan. That includes your Medicare Supplement coverage — is it still the right fit, still priced competitively, still covering what you need? A lot of people haven’t checked in years.
If you want a second set of eyes on any of it — your Part D options, your Supplement plan, or just want someone to walk through what Open Enrollment actually means for your situation — give me a call or visit the website. No pressure, no call center, just a real conversation about what makes sense for you.
Medicare AEP 2026 Arizona — the Annual Enrollment Period — runs October 15 through December 7, 2026. Any changes you make take effect January 1, 2027. Here’s what Medicare AEP 2026 actually covers, what’s new for 2026, and why it’s worth a look even if you’re not planning to change anything.
What Medicare AEP 2026 Arizona Actually Covers
AEP is specifically the window for changing Medicare Advantage and Part D prescription drug coverage — joining, switching, or dropping either. It is not the enrollment window for Medicare Supplement (Medigap) plans. Medigap doesn’t have a single national enrollment period the way Advantage and Part D do; you can generally shop for a Medigap plan at any time, though outside your original Medigap Open Enrollment window or a guaranteed-issue situation, carriers can medically underwrite you.
Why Medicare AEP 2026 Arizona Still Matters for Medigap Holders
Even though Medigap itself isn’t on the AEP calendar, fall is still the right time to check a few things:
Your Part D drug plan — if you carry a standalone Part D plan alongside Medigap, its formulary and pricing can change every year, so it’s worth reviewing during AEP (I’m not licensed to sell Part D plans myself, but it’s still worth checking on your end or with your Part D agent).
Your Medigap premium — carriers commonly adjust Medigap rates at renewal. If yours went up significantly, it’s worth comparing what else is available, especially if your health has stayed steady since you first enrolled.
Whether Medicare Advantage still makes sense for you — if you’re on an Advantage plan and considering a move to Original Medicare plus Medigap, AEP is when you’d drop the Advantage plan; just know that moving to Medigap afterward may involve medical underwriting unless you qualify for guaranteed issue.
Medicare AEP 2026 Arizona: What’s New This Year
A few concrete numbers worth knowing this year:
According to SSA.gov, the standard Medicare Part B premium is $202.90/month for 2026, up from $185/month in 2025.
The Part D out-of-pocket cap increased from $2,000 (2025) to a higher indexed amount for 2026, and enrollees can still choose to spread that cost across the year in equal monthly payments instead of paying it early.
Some insurers are exiting the Medicare Advantage market or reducing plan offerings for 2026 — if that affects your current plan, you’ll likely get a notice from your carrier this fall, and it’s worth acting on it rather than setting it aside.
A Few Common Mistakes During AEP
Comparing plans on premium alone, without confirming your doctors and pharmacy are still in-network. Waiting until the first week of December to make a decision, which leaves little room to fix a mistake before the deadline. Assuming a plan that worked well last year hasn’t changed — formularies and networks are re-evaluated annually, not locked in.
How I Can Help
When you call, I spend about five minutes learning your situation, then I go research quotes across multiple Medigap carriers — not just one company’s price. You get a detailed, side-by-side quote by email, and you review it on your own time. No pressure to decide on the call. I don’t sell Medicare Advantage or Part D plans, so I’m not working an angle when I tell you whether your current Medigap setup still makes sense or not.
I’ve laid out the full turning-65 process in this Medicare checklist, and if Mayo Clinic access matters to your plan choice, I’ve covered exactly which plans keep it in-network in this breakdown.
Frequently Asked Questions
What are the AEP dates for 2026?
Medicare’s Annual Enrollment Period runs October 15 through December 7, 2026. Changes made during this window take effect January 1, 2027.
Does AEP apply to Medicare Supplement (Medigap) plans?
No. AEP covers Medicare Advantage and Part D prescription drug plan changes. Medigap doesn’t have a fixed annual enrollment period — you can generally apply anytime, though medical underwriting may apply outside your original Medigap Open Enrollment window or a guaranteed-issue situation.
What is the Medicare Part B premium for 2026?
The standard Part B premium for 2026 is $202.90 per month, up from $185 per month in 2025. Higher-income enrollees pay more.
What happens if I miss the December 7 AEP deadline?
If you miss AEP and don’t qualify for a Special Enrollment Period, you’ll generally need to wait for the Medicare Advantage Open Enrollment Period (January 1 – March 31), which has more limited options — it only allows switching between Medicare Advantage plans or dropping Advantage for Original Medicare, not adding or changing a standalone Part D plan.
Mayo Clinic Arizona insurance questions come up constantly — Mayo in Scottsdale and Phoenix is one of the top reasons people choose to stay in Arizona for their healthcare. But here’s what a lot of people don’t find out until they’re already sitting in the waiting room with the wrong coverage: not every health plan gets you in the door. Here’s exactly what does — and doesn’t — work.
Mayo Clinic Arizona Insurance: The Short Answer
Original Medicare + a Medicare Supplement (Medigap) — accepted at Mayo Clinic Arizona, no exceptions.
Medicare Advantage — Mayo Clinic does not accept non-contracted Medicare Advantage plans. If you’re on one, don’t assume you’re covered.
ACA Marketplace plans (Ambetter, Blue Cross Blue Shield, Cigna, Oscar, UnitedHealthcare Marketplace) — not accepted at Mayo Clinic Arizona as of 2026.
Private off-exchange PPO plans (like UHC Choice Plus or Aetna Open Choice PPO) — accepted, but these are underwritten plans you buy directly, not subsidized Marketplace plans.
If You’re on Medicare: The Plan G vs. Plan N Detail That Matters at Mayo
Mayo Clinic Arizona accepts Original Medicare and any Medicare Supplement carrier — that part is straightforward. But there’s a detail specific to the Arizona location that trips people up: unlike Mayo’s Florida campus, Mayo Clinic Arizona does not accept full Medicare Assignment. That means they’re allowed to bill up to 15% above what Medicare approves — what’s called an “excess charge.”
This is exactly where the choice between Medigap Plan G and Plan N actually matters. Plan G covers those excess charges in full. Plan N does not — so if you’re a Plan N holder being treated at Mayo Clinic Arizona, you could see a bill for that difference. I’ve written a full breakdown of Plan G vs. Plan N in Arizona if you want the complete comparison, but if Mayo Clinic access matters to you specifically, that excess-charge detail alone is often reason enough to choose Plan G.
You’ll also need a referral to be seen at Mayo, and in some cases prior authorization for specific tests or procedures — standard Medicare rules, not something unique to Mayo.
Why Medicare Advantage Is the Riskiest Choice Here
Mayo Clinic’s own guidance is direct: they do not accept non-contracted Medicare Advantage plans. If you’re 65+ and want reliable access to Mayo, a Medicare Advantage plan puts that access at the mercy of whatever network your specific carrier has negotiated — and that can change year to year. I don’t sell Medicare Advantage, and this is one of the clearest real-world examples of why: here’s the full explanation.
If You’re Under 65: The ACA Marketplace Doesn’t Get You In
This is the one that catches people off guard. None of the individual ACA Marketplace plans sold in Arizona for 2026 — not Ambetter, not Blue Cross Blue Shield, not Cigna, not Oscar, not UnitedHealthcare’s Marketplace plans — are accepted at Mayo Clinic Arizona. Banner|Aetna and BCBS Statewide PPO, which used to offer some access, are no longer on the ACA Marketplace at all as of 2026.
To get Mayo Clinic access under 65, you generally need a private, off-exchange PPO plan — options like UHC Choice Plus or Aetna’s Open Choice PPO network are commonly accepted. These aren’t Marketplace plans, so there’s no subsidy, and most are medically underwritten, meaning your health history affects your rate and whether you qualify at all. That’s a real tradeoff: broader network access in exchange for underwriting and no tax credit.
Frequently Asked Questions
Does Mayo Clinic Arizona accept Medicare?
Yes — Original Medicare plus a Medicare Supplement (Medigap) is accepted at Mayo Clinic Arizona with no exceptions.
Does Mayo Clinic Arizona accept Medicare Advantage plans?
Mayo Clinic does not accept non-contracted Medicare Advantage plans. If you’re on a Medicare Advantage plan, don’t assume you’re covered — check your specific plan’s contract status before you need care.
Does Mayo Clinic Arizona accept ACA Marketplace plans?
No. As of 2026, ACA Marketplace plans — including Ambetter, Blue Cross Blue Shield, Cigna, Oscar, and UnitedHealthcare Marketplace — are not accepted at Mayo Clinic Arizona.
What insurance do I need to see a doctor at Mayo Clinic Arizona if I’m under 65?
Private off-exchange PPO plans, such as UHC Choice Plus or Aetna Open Choice PPO, are accepted at Mayo Clinic Arizona. These are medically underwritten plans purchased outside the ACA Marketplace.
How I Can Help
Whether Mayo Clinic access is the deciding factor for you or just one piece of a bigger decision, I’ll compare your options — Medigap, ACA Marketplace, or private PPO — against what you actually need, including which hospitals and doctors matter to you. I don’t sell Medicare Advantage, and I’ll tell you plainly when a plan won’t get you where you want to go.
Serving Scottsdale, Phoenix, Surprise, Peoria, Glendale, Mesa, Chandler, Gilbert, and all of Arizona.
American Insurance Benefits | 14955 W Bell Rd #8031, Surprise, AZ 85374 | Licensed Arizona Insurance Broker since 1999. This page reflects Mayo Clinic Arizona’s publicly stated insurance policies as of 2026; always confirm current network status directly with Mayo Clinic before making a coverage decision.
Andy Orlikoff • NPN #7558435 • Licensed in Arizona, North Carolina & South Carolina
Verify this license at nipr.com Follow us on Facebook