If you’re shopping for a Medicare Supplement in North Carolina, there’s one enrollment window that matters more than almost any other — and most people don’t find out about it until it’s already closed. I’m licensed here in North Carolina and South Carolina, and Medicare Supplement North Carolina questions are among the ones I get asked most. So let me walk you through it plainly.
What the Medicare Supplement North Carolina open enrollment window actually is
Your Medicare Supplement (Medigap) Open Enrollment Period is a one-time, six-month window. It starts the month you’re both 65 or older and enrolled in Medicare Part B. During those six months, insurance companies in North Carolina have to sell you any Medigap plan they offer, no matter your health history. They can’t turn you down, they can’t charge you more because of a health condition, and they can’t make you wait out a pre-existing condition.
That’s a powerful protection. It’s also temporary.
What changes after the window closes
Once those six months are up, the rules flip. Insurance companies in North Carolina can use medical underwriting — which means they get to look at your health history and decide whether to accept you, and at what price. A condition you didn’t think twice about can suddenly mean a higher premium, or a flat denial.
I want to be honest with you about this, because it’s the part that catches people off guard: waiting isn’t free. The healthy time to lock in a Medigap plan is during that first window, before anything on your medical record gives a company a reason to say no.
Turning 65 later? North Carolina has a rule worth knowing
Here’s something specific to our state that a lot of folks miss. If you qualified for Medicare under 65 due to a disability, North Carolina law guarantees you access to certain Medigap plans — Plans A, D, and G — even before you turn 65. And then, when you do reach 65, you get a brand-new, full six-month Open Enrollment Period to buy any standardized plan at the standard rate, with no health screening at all.
That fresh window at 65 is a genuine second chance, and it’s written into state law. Not every state offers it. If this is your situation, don’t let that window slip by the way the first one might have.
What if you already missed your window?
Don’t panic. Missing your Open Enrollment Period doesn’t mean you’re out of options — it means the path looks different. You can still apply for a Medigap policy any time; the company just gets to underwrite it. Depending on your health, you may still qualify at a good rate. And in certain situations, you may have guaranteed-issue rights that reopen a protected window — for example, if you lose other coverage.
This is exactly the kind of thing worth a quick phone call before you assume the door is shut. There are 48 companies selling Medigap plans in North Carolina, and because the plans are standardized, a Plan G is a Plan G no matter whose name is on it — so the real work is finding the company that will take you at the best price.
Why I don’t sell Medicare Advantage
You’ll notice I keep talking about Medigap, not Medicare Advantage. That’s on purpose. I don’t sell Medicare Advantage plans, and I don’t plan to start. I’ve watched too many people get pulled in by a low premium, then run into network restrictions and denied care right when they needed the plan to work. Even here in North Carolina, major health systems have been walking away from some Advantage plans. I’d rather offer you coverage I’d put my own family on.
Let’s figure out your Medicare Supplement North Carolina options together
Whether you’re coming up on 65, already past your Open Enrollment Period, or just not sure where you stand, I’m happy to sort it out with you — by phone, text, or email, whatever’s easiest. There’s no cost to work with me, and the rate is the same as going direct. I work for you, not the insurance company.
Call or text me at (910) 760-2124, or email Andy@coastalcarolinahealth.com. A real person answers — no call centers.
American Insurance Benefits Now Serves North Carolina and South Carolina
For nearly 25 years, I’ve been helping Arizona families cut through the confusion of health insurance shopping — comparing plans honestly, explaining the fine print, and making sure nobody gets stuck with coverage that doesn’t actually work when they need it. Today, I’m excited to share that I’m expanding that same approach to North Carolina and South Carolina.
I’m now licensed and ready to help clients in North Carolina and South Carolina, in addition to Arizona.
Why I’m Expanding to North Carolina and South Carolina
I split my time seasonally between Arizona and North Carolina, so this isn’t a broker calling in from across the country — it’s someone who spends real time in both markets. That matters, because health insurance is local. Carrier networks, plan availability, and pricing all vary by state, and the best plan for a client in Surprise, Arizona often looks nothing like the best plan for someone in the Carolinas.
What Stays the Same
Whether you’re in Arizona, North Carolina, or South Carolina, the way I work with clients doesn’t change:
Independent, not captive. I compare plans across many top carriers, not just one company’s product line, so you get an honest side-by-side comparison.
Always free to you. I’m paid by the carrier, not by you. Your premium is exactly the same whether you use a broker or go direct.
No Medicare Advantage. I don’t sell it, and I’ll explain why Medicare Supplement often protects you better over the long run.
PPO alternatives and Short-Term Medical. For healthy clients who don’t need a full ACA plan’s price tag, these options can mean real savings without giving up broad provider access.
Everything by phone, text, or email. No office visits required, no automated systems, no spam calls — just a straightforward conversation.
North Carolina and South Carolina: What’s Different
For Arizona clients, I continue to specialize in finding private plans that keep Mayo Clinic in-network — something most standard ACA plans exclude entirely. For clients in North Carolina and South Carolina, I bring that same careful attention to your local carrier networks and plan options.
Get Started
If you’re in Arizona, call or text me at (623) 742-3878. If you’re in North Carolina or South Carolina, reach me at (910) 760-2124. Or head to azhealth.us to request a free quote.
I look forward to helping more families get covered — without the stress, and without the sales pitch.
If you’re feeling the ACA subsidy cliff hit your premium this year, you’re not imagining things. The enhanced subsidies that kept Marketplace premiums manageable from 2021 through 2025 expired at the end of last year, and the ACA subsidy cliff is back in force for 2026 at the original 400% federal poverty level cutoff. For a single person, that cutoff sits around $62,600 in income. Cross it by even a dollar, and your premium tax credit disappears completely — not reduced, gone. You can check the current federal poverty level thresholds directly at healthcare.gov.
I’ve had a lot of calls this year from Arizona clients who did everything right at open enrollment and are still stunned by what showed up on their bill in month two or three. So let’s talk about what your actual options are right now, mid-year, if you’re one of them.
The ACA Subsidy Cliff: What You Can and Can’t Do
The federal Marketplace only reopens outside of open enrollment if you have a qualifying life event — losing other coverage, getting married, having a baby, or a permanent move, among a few others. Deciding you can no longer afford your plan isn’t a qualifying event. Neither is getting dropped for non-payment. So if you’re already enrolled and the ACA subsidy cliff caught you, you generally can’t just walk back into the Marketplace and pick something cheaper.
That doesn’t mean you’re stuck with your current plan, though. It means the fix has to come from somewhere other than the Marketplace itself.
Off-Exchange Plans Are Worth a Look
Here’s something a lot of people don’t realize: ACA-compliant plans are available off-exchange, year-round, directly through carriers or through a broker like me. If you landed above the 400% cliff, you weren’t getting a subsidy anyway — so an off-exchange plan gives you the same coverage rules and often the same network, without needing a special enrollment period to switch into it. For households in exactly your situation, this is usually the cleanest path.
PPO Alternatives Deserve a Serious Look Too
This is where I spend most of my time with clients right now. If you’re relatively healthy and rarely use your coverage beyond routine visits, a full ACA plan priced at full freight may not be the best use of your money. Short-term medical and PPO alternative plans can offer meaningfully lower premiums with broad provider networks — including, in the right plan, access to Mayo Clinic, which most standard ACA plans exclude entirely. These aren’t a fit for everyone, and I’ll tell you honestly if they’re not a fit for you. But for a lot of Arizona families right now, they’re the difference between coverage they can actually afford and coverage they’re quietly resenting every month.
If You’re Close to the Cliff, Watch Your Income
If your income is hovering right around that 400% line, a few strategies can help you stay under it — and they’re worth knowing about before year-end, not after:
HSA contributions reduce your ACA-specific modified adjusted gross income (MAGI). As of this year, all Bronze Marketplace plans are HSA-eligible, which opens this option to more people than before.
Traditional IRA contributions work the same way — they lower MAGI, which is what your subsidy eligibility is actually based on.
Qualified Roth withdrawals don’t count toward MAGI at all, so if you need to supplement income mid-year, pulling from a Roth won’t push you closer to the cliff the way other income sources will.
If you’re self-employed or your income varies month to month, it’s worth tracking your estimated MAGI throughout the year rather than waiting until tax time to find out you went over. Going over the line even briefly can mean paying back subsidies you already received.
The Real Mistake to Avoid
The biggest mistake I see is people treating “alternative coverage” as a straight swap for their old ACA plan. It isn’t, and it shouldn’t be sold to you that way. A full ACA plan bundles preventive care, specialist visits, hospitalization, and prescription coverage into one plan with a managed deductible. A short-term or PPO alternative plan works differently, and figuring out whether it actually covers what you need takes an honest conversation — not a sales pitch.
Beat the ACA Subsidy Cliff: Let’s Look at Your Numbers
Every household’s situation here is different — your income, your health, which doctors you need to keep, and how close you are to that 400% line. If your premium jumped this year and you want an honest second opinion on what else is out there, I’m happy to walk through it with you. No pressure, no cost, and I’ll tell you plainly if your current plan is still your best option.
Plan G vs Plan N — when choosing a Medicare Supplement plan in Arizona, this is the comparison that matters most. Both plans are popular. Both cover most of what Original Medicare leaves behind. However, they handle office visits and cost-sharing differently. In this guide, you’ll see exactly how Plan G vs Plan N compares — so you can choose the right plan for 2026.
What Plan G and Plan N Both Cover
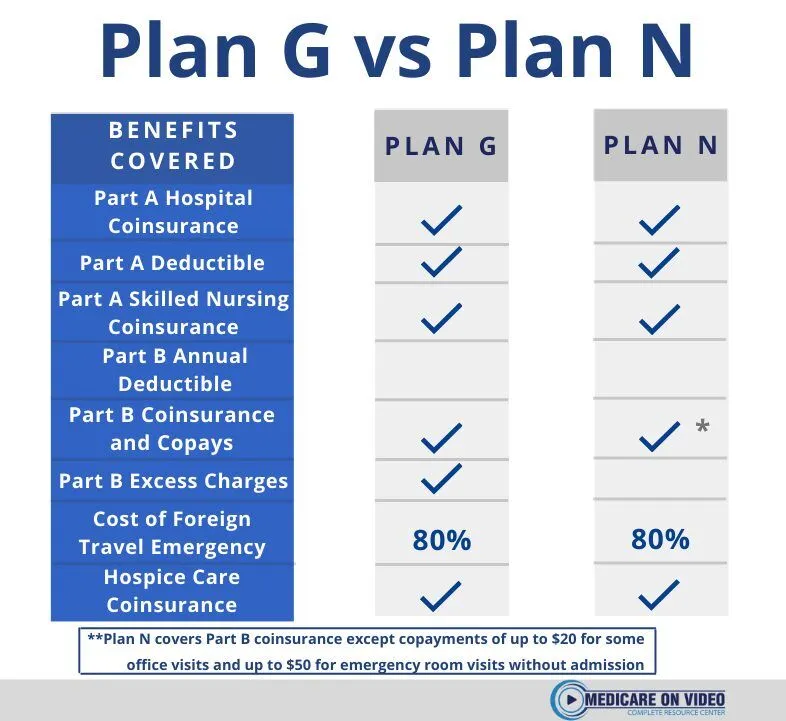
First, it helps to know what these two plans share. Both Plan G vs Plan N cover the following:
Medicare Part A coinsurance and hospital costs
Medicare Part A deductible ($1,736 in 2026)
Medicare Part A hospice care coinsurance
Skilled nursing facility coinsurance
Medicare Part B coinsurance — with one key difference explained below
Foreign travel emergency care up to plan limits
In addition, both plans require you to pay the Part B deductible ($283 in 2026) once per year. After that, coverage kicks in. So far, they look nearly identical. The differences, however, matter a lot depending on how often you use your insurance.
Plan G vs Plan N: The Key Differences
Plan G covers 100% of your Medicare Part B coinsurance. Therefore, after your Part B deductible, you owe nothing for covered outpatient care.
Plan N covers most Part B coinsurance — but not all. Specifically, Plan N has these out-of-pocket costs:
Up to $20 copay per office visit
Up to $50 copay per emergency room visit (waived if admitted)
Part B excess charges — if a doctor doesn’t accept Medicare assignment, you pay the difference between their rate and Medicare’s approved amount
Most Arizona doctors accept Medicare assignment. As a result, excess charges rarely come up. However, the office visit copays do add up if you see doctors often. That’s the core of the Plan G vs Plan N decision.
How Premiums Compare in Arizona
Plan N typically costs $20–$40 less per month than Plan G in Arizona. Therefore, over a full year, you could save $240–$480 in premiums with Plan N.
However, that savings only holds if your copays stay below the premium difference. For example, if you visit the doctor six times per year, that’s up to $120 in Plan N copays. In that case, Plan N still wins on price. On the other hand, frequent visits or ER trips can close the gap quickly.
The bottom line: run the numbers for your situation. That’s exactly what I do for clients at no charge.
Who Should Choose Plan G
Plan G makes the most sense in these situations:
You have ongoing health conditions or frequent doctor visits
You want predictable costs with no copay surprises
You travel often and may see out-of-network providers
You simply want the most comprehensive coverage available
In short, Plan G is the “set it and forget it” option. After your Part B deductible, your costs are done for the year.
Who Should Choose Plan N
Plan N works well in these situations:
You are generally healthy and see a doctor only a few times per year
You want to lower your monthly premium
Your doctors all accept Medicare assignment
You are comfortable paying a small copay at visits
Furthermore, Plan N is a smart choice for people who want solid Medigap coverage without paying for benefits they rarely use.
Plan G vs Plan N: Carriers in Arizona
Both plans are standardized by the federal government. Therefore, the benefits are identical no matter which insurance company you buy from. What differs between carriers is the monthly premium and the company’s rate history.
Whether you choose Plan G or Plan N, timing is critical. When you first enroll in Medicare Part B, you receive a 6-month Medigap open enrollment window. During this period, insurance companies cannot deny you or charge more based on health history.
After this window closes, however, insurers can use medical underwriting. Consequently, pre-existing conditions could affect your options or your premium. This window only happens once. Therefore, if you’re turning 65, get your Medigap plan in place before your birthday month.
I’m Andy Orlikoff, an independent Medicare Supplement broker in Surprise, AZ. I’ve been helping Arizona residents compare Plan G vs Plan N and enroll in the right coverage since 2004. I don’t sell Medicare Advantage — just honest Medigap guidance at no cost to you.
I’ll pull side-by-side quotes from multiple carriers and walk you through the numbers. You decide what fits. I handle the enrollment.
One of the most common complaints about the ACA marketplace is that it limited health insurance choice — pushing most plans toward HMO-style networks and eliminating the flexible PPO options that many Americans preferred. However, ACA health insurance alternatives do exist for people who want more flexibility than the marketplace offers. Here’s what’s available in Arizona in 2026.
How the ACA Limited Health Insurance Choice
Before the ACA, many individuals had access to a range of private PPO plans with broad networks and no referral requirements. After 2014, most of those plans disappeared from the individual market — replaced by ACA-compliant HMO and EPO plans with narrower networks and strict in-network requirements.
The result: millions of Americans found themselves in plans that didn’t include their doctors, required referrals to see specialists, or excluded major hospitals like Mayo Clinic.
ACA Health Insurance Alternatives in Arizona
Several ACA health insurance alternatives have emerged to serve people who want more flexibility — especially those who don’t qualify for large ACA subsidies:
Off-exchange PPO plans — Available from select carriers outside the ACA marketplace. Broader networks, no referral requirements, no subsidy eligibility. Ideal for healthy individuals earning above subsidy thresholds.
Short-term medical plans — Provide PPO-style access at lower premiums. Not ACA-compliant but useful for healthy individuals between coverage periods.
Health sharing ministries — A non-insurance alternative for cost-sharing among members. Not a substitute for comprehensive coverage but used by some as a lower-cost option.
Level-funded group plans — Self-employed individuals and small business owners may qualify for group-style coverage with broader options than the individual marketplace.
Does Mayo Clinic Accept ACA Marketplace Plans?
This is one of the most important questions Arizona residents ask. Most ACA marketplace plans in Arizona do not include Mayo Clinic Arizona in their networks. Select off-exchange PPO plans do. If keeping Mayo Clinic access is a priority, this is a key reason to explore ACA health insurance alternatives.
Free Help Comparing Your Options in Arizona
I’m Andy Orlikoff, an independent health insurance broker in Surprise, AZ. I compare ACA health insurance alternatives alongside marketplace plans — showing you exactly what each option covers, what it costs, and which doctors are included. My help is free.
 American Insurance Benefits Now Serves North Carolina and South Carolina