Medicare Open Enrollment 2027 Arizona officially opens October 15 and runs through December 7 — seven weeks to review your coverage and make changes for next year. But the window itself isn’t the hard part; the hard part is the stack of notices that show up beforehand, which most people skim past without realizing what each one is actually telling them.
Medicare Open Enrollment 2027 Arizona: The Notices Already in Your Mailbox
By late September, you should have received your Annual Notice of Change (ANOC) and Medicare & You handbook. The ANOC is the one worth reading closely — it spells out exactly what’s changing in your Medicare Advantage or Part D plan for 2027: copay changes, dropped providers, and medications that may no longer be covered. If a plan is leaving your county or shutting down entirely, that comes as a separate Plan Non-Renewal or Termination Notice, which can arrive at any time and opens its own special enrollment period outside the normal AEP window.
On October 14, the 2027 cost-of-living adjustment (COLA) is announced, and Medicare’s 2027 Part B premium and Part A/B deductibles follow in late October or early November. Those two numbers are what let you actually estimate next year’s costs instead of guessing. IRMAA determination letters and Social Security COLA notices follow in November and December, showing your actual 2027 premiums and any income-based surcharges.
What to Actually Check Before December 7
With the ANOC in hand, confirm three things: that your current doctors and hospitals are still in network, that your medications are still covered at the tier you expect, and that your plan’s costs still fit your budget once the new premium and deductible numbers are out. It’s also worth pulling your 2026 Medicare Summary Notices or Explanations of Benefits to check for services you didn’t actually receive — errors are more common than people assume, and AEP is a natural time to catch them.
If Something Doesn’t Add Up
If your current plan no longer fits — a doctor dropped from the network, a medication moved to a higher tier, or a cost increase that doesn’t work for your budget — Open Enrollment is your window to switch before December 7, with new coverage taking effect January 1. Setting up a my Social Security or Medicare.gov account can get these notices to you by email sooner, so you’re not relying on paper mail timing.
Not sure what your ANOC actually means for your coverage next year?
Free, no-pressure review before December 7 — I’ll help you read through the notices and compare your options.
*This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Dates and notice descriptions are from Kiplinger’s 2027 Medicare Open Enrollment guide; confirm your own plan’s specific changes directly through your ANOC or Medicare.gov.*
Choosing Medicare Advantage at 65 feels like a low-risk decision, especially with a low or zero monthly premium. The catch tends to show up years later: going from Medicare Advantage to Medigap can be much harder than getting into Medicare Advantage ever was. That’s worth knowing this fall, with Medicare’s Annual Election Period running October 15 through December 7.
Why Medicare Advantage to Medigap Is Harder Than It Looks
Federal law bars Medicare Advantage plans from turning you down or charging you more because of your health — you can enroll during your Initial Enrollment Period, the fall Annual Election Period, or a Special Enrollment Period, sick or not. Medigap plays by a different rulebook. You get one federally protected window, the Medigap Open Enrollment Period, which lasts six months and starts the first month you’re both 65 or older and enrolled in Medicare Part B. During those six months, any insurer selling Medigap in your state has to offer you any plan it sells, at its best available rate, regardless of your health history.
After those six months close, federal protections end and state law takes over. In most states, a Medigap insurer reviewing a later application can ask full health questions, charge a higher rate based on the answers, apply a waiting period of up to six months for a pre-existing condition, or decline the application outright.
Why 72 Is the Wrong Age to Try It
A retiree who picked a zero-premium Medicare Advantage plan at 65 often wants Medigap by 72, right around when prior authorization requirements, narrow provider networks, and out-of-network billing start to matter more. By then, a diagnosis or a longer prescription list picked up along the way can turn a simple application into a difficult one — or an impossible one, in a state without extra protections.
What Can Still Open the Door
A few situations restore your guaranteed-issue right, no matter how long it’s been:
The 12-month trial right. If you enrolled in Medicare Advantage when you first became eligible for Medicare, you have 12 months to drop the plan and buy any Medigap policy sold in your state without underwriting. The same 12-month right applies if you dropped a Medigap policy to try Medicare Advantage for the first time.
Your plan leaves the market. Guaranteed issue also kicks in if your Medicare Advantage plan exits the market, ends its contract in your service area, or you move outside the plan’s coverage area.
Your state’s own rules. A handful of states — Connecticut, Massachusetts, and New York among them — require Medigap insurers to issue policies year-round without underwriting. Others, including California, Oregon, and Nevada, give current Medigap policyholders an annual window, often tied to their birthday, to switch plans without health questions. Arizona is not one of the states with a birthday-rule or continuous guaranteed-issue law as of this writing.
Since Arizona doesn’t have one of these state-level protections, the federal six-month window and the situations above are what determine whether you can switch without medical underwriting here.
What to Decide Before Part B Starts
If you’re approaching 65, you’re deciding whether to use the one federally protected chance to buy Medigap on an insurer’s best terms — that decision is worth more weight than just comparing this year’s premium. If you’re already on Medicare Advantage and past your six-month window, it’s worth confirming whether a guaranteed-issue right currently applies to your situation before assuming a later switch is off the table, or assuming it’s automatically available.
Wondering whether a Medicare Advantage to Medigap switch is realistic for you? Call (623) 742-3878 for a free, no-pressure conversation — as an independent broker who doesn’t sell Medicare Advantage, I can walk through what applies to your specific timeline and situation.
This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Guaranteed-issue rules can be complex and vary by exact circumstance — confirm your specific situation with Medicare.gov, your State Health Insurance Assistance Program (SHIP), or a licensed agent before making a coverage decision.
If you have a Medicare Advantage plan, one of the biggest Medicare Advantage changes 2027 brings is arriving in your mailbox over the next couple of weeks. Every Medicare Advantage member with a continuing plan receives an Annual Notice of Change (ANOC) by September 30, spelling out what’s different about the plan for 2027 — and this year, more of those letters are likely to carry real changes than usual.
Why the Medicare Advantage changes 2027 brings are bigger than usual
Insurers have been pulling back from certain Medicare Advantage markets as they face rising medical costs and tighter government reimbursement. One large carrier already confirmed in late July that it’s exiting select markets for the 2027 plan year, a move expected to affect roughly 600,000 members nationwide. That follows an unusually disruptive 2026: close to 2.9 million Medicare Advantage enrollees had to find new coverage this year because their plan exited their market or was discontinued altogether — a rate about ten times the historical average.
What to actually check in your ANOC
A flat premium doesn’t mean nothing changed. Read past the monthly cost and check:
Deductibles and copays for the visits and care you actually use
Your maximum out-of-pocket limit — a modest premium bump can be dwarfed by a jump here
Whether your prescriptions are still covered, and at what tier
Whether your doctors, specialists, and preferred hospital are still in-network — plans can shrink a network even when the plan name stays the same
Extra benefits like dental, vision, hearing, or transportation, which are often the first things cut
Whether the plan still covers your county at all
If your letter says the plan is changing, it’s still available — you don’t have to switch, but it’s worth comparing against the alternatives. If instead you get a separate Plan Non-Renewal Notice, typically mailed in October, your specific plan is leaving Medicare altogether and you’ll need to pick something new before coverage ends.
The timeline ahead
By September 30: Your ANOC should arrive
October 1: 2027 plan details become public — a good time to start comparing
This is exactly the kind of yearly uncertainty that led me to stop offering Medicare Advantage altogether. With a Medicare Supplement (Medigap) plan alongside Original Medicare, your coverage isn’t tied to a shifting network or a carrier’s market decisions each fall — you get consistent rules and predictable costs, nationwide, year after year. If you’re facing a plan change or non-renewal notice this fall, that’s a good moment to see what Medigap coverage would actually look like for your situation.
Getting your ANOC and not sure what it means for you? Call (623) 742-3878 or reach out through the contact form, and as an independent Arizona health insurance broker I’ll walk through it with you — no pressure, just a clear read on your options before the December 7 deadline.
This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Please review your own Annual Notice of Change letter for details specific to your current plan.
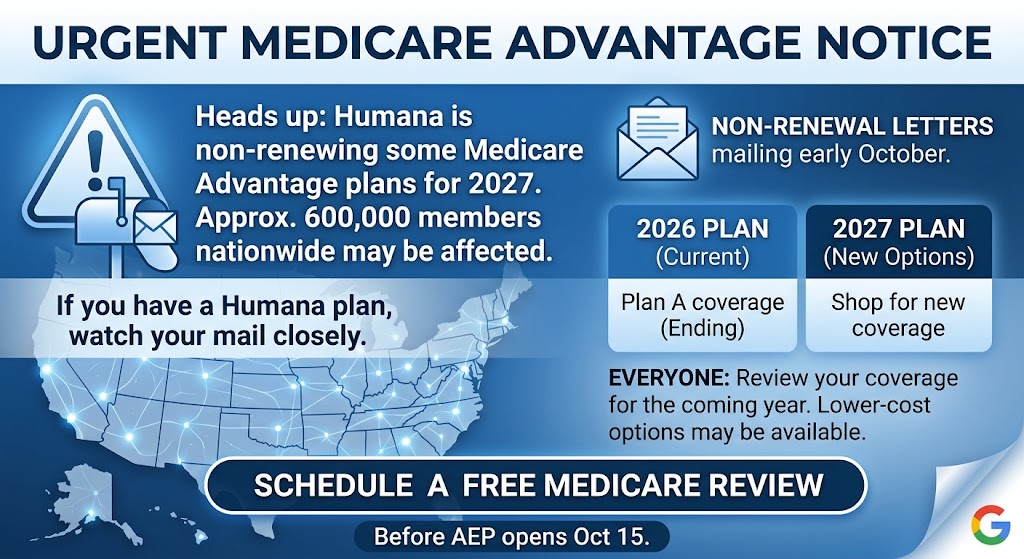
Humana has confirmed it’s exiting a number of Medicare Advantage plans for 2027, affecting roughly 600,000 members nationwide. If you have a Humana Medicare Advantage Arizona plan, this is worth paying attention to — whether or not you’ve received anything in the mail yet.
What’s actually happening
Humana is discontinuing plans it says are the “lower tail of profitability” for 2027 — mostly plans rated 3.5 stars or lower. Non-renewal letters are expected to go out starting in early October, right as Medicare’s Annual Enrollment Period opens on October 15. If your plan is affected, you’ll be notified directly by Humana, but the letter alone won’t tell you what to do next.
Why this matters even if you’re not sure you’re affected
Humana hasn’t published a full list of which specific plans or counties are impacted. The only way to know for certain is to watch your mail closely this fall — and to have a plan for what comes next if a non-renewal letter shows up. Waiting until you’re holding the letter to start comparing options means doing it under time pressure, right in the middle of AEP’s busiest weeks.
Humana Medicare Advantage Arizona: Your Options If Your Plan Is Dropped
If your Humana Medicare Advantage plan is discontinued, you’re not left without coverage — you’ll have a special enrollment window to pick something new. Depending on your situation, that could mean:
Enrolling in a different Medicare Advantage plan from another carrier
Moving to Original Medicare paired with a Medicare Supplement (Medigap) plan and a stand-alone Part D drug plan
Reviewing whether your current doctors and prescriptions are still covered under any new option you’re considering
As an independent Arizona broker, I’m not tied to steering you back into another Humana Medicare Advantage Arizona product — the goal is finding whatever actually fits your coverage needs now.
What to do this fall
Whether or not you get a letter, it’s worth a quick check-in before AEP opens October 15. If you are notified that your plan is being discontinued, reach out as soon as you get the letter — the sooner we start comparing options, the less rushed the decision.
Received a non-renewal letter, or just want to make sure you’re covered either way? Call (623) 742-3878 for a free, no-pressure review. As an independent Arizona health insurance broker, I can also show you how a Medicare Supplement plan works if you would rather not depend on one plan’s network and market decisions.
This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare, Humana, or any government agency. Please review any notice you receive directly from your carrier for details specific to your plan.
If you or someone you love is on a Medicare Advantage plan, the ground just shifted under your feet — and most people don’t yet realize it.
A peer-reviewed research letter published in JAMA in February 2026, from a team at the Johns Hopkins Bloomberg School of Public Health, put a hard number on what many of us in this business have been watching unfold: roughly 2.9 million Medicare Advantage members — about 1 in 10 — are being forced out of their plans for 2026. Their insurance company either pulled out of the county entirely or shut down the plan they were on.
For context, the historical rate of forced disenrollment ran at about 1% from 2018 through 2024. It jumped to 6.9% in 2025, and now sits at 10% for 2026. That’s a tenfold increase in two years.
Why This Is Happening
The short version: several large insurers looked at rising medical costs and shifting federal payment rules, and decided they couldn’t make the Medicare Advantage math work in certain markets anymore. So they cut plans. Some smaller carriers exited entirely.
The people hit hardest, according to the research, were enrollees in PPO plans, plans from smaller carriers, plans with lower star ratings, and rural counties. If any of that describes your current plan, you should assume you’re closer to this problem than farther from it.
What Happens Next If You Get Forced Off Your Plan
Here’s the part almost no one talks about until it’s too late.
When your Medicare Advantage plan exits your county, you typically get a Special Enrollment Period to pick a new plan. That sounds like a solution. In many cases it isn’t.
Your options usually break down into three uncomfortable choices:
Enroll in a different Medicare Advantage plan — often one with a narrower network, a different provider list, and different drug coverage. Your current doctors may or may not be in-network. Your prescriptions may or may not be covered the same way.
Go back to Original Medicare — which covers about 80% of costs, leaving you exposed to the remaining 20% with no annual out-of-pocket cap. That’s why most people on Original Medicare add a Medicare Supplement (Medigap) plan to fill the gap.
Go back to Original Medicare and try to buy a Medigap plan — this is where the catch lives.
The Medigap Catch That Blindsides People
Federal law protects your right to buy any Medigap plan sold in your state, with no health questions asked, during a specific one-time six-month window that starts when you’re first 65 and enrolled in Medicare Part B.
If you missed that window because you went straight into Medicare Advantage, and you now need a Medigap plan because your Advantage plan disappeared, in most states the insurance company can look at your health history and either turn you down or raise your rate.
There are some situations that create guaranteed-issue rights — protected windows where you can buy Medigap without medical underwriting. Losing your Medicare Advantage plan because it exited your area is one of them. But the timing is tight (typically 63 days after your coverage ends) and the plans you’re guaranteed access to are a narrower set than you’d have during the original Open Enrollment Period.
This is why I’ve said for years, and will keep saying: the decision to enroll in Medicare Advantage isn’t fully reversible. It looks like a low-cost option going in. When the exit door slams shut, the underwriting door often does too.
What Medicare Beneficiaries Should Do Right Now
If you’re on a Medicare Advantage plan, here’s the checklist I’d walk any client through:
Read your Annual Notice of Change carefully. This letter comes every fall. It tells you whether your plan is continuing, changing, or exiting for the coming year.
Check whether your doctors and prescriptions are still covered. Even if your plan continues, the network and formulary can change year to year.
Know your guaranteed-issue rights. If your plan is exiting your area, you have a limited window to buy certain Medigap plans without health underwriting. Don’t miss it.
Talk to someone who doesn’t sell Medicare Advantage. I don’t. That’s a deliberate choice, not an oversight. If you’re getting advice only from someone who does, you’re getting one side of the picture.
Why I Don’t Sell Medicare Advantage
The Johns Hopkins study is the clearest third-party validation I’ve seen of the position I’ve held since day one of my practice. Medicare Advantage plans are heavily marketed, often with no monthly premium and extra perks that sound great. What the commercials don’t tell you is that the insurance company can leave the market and take your coverage with them — and once your health changes, getting back to Original Medicare with a supplement can be difficult or impossible.
I stick to Medicare Supplement plans, where you keep your own doctors, there’s no network to fight, and the coverage doesn’t disappear when a carrier decides a county isn’t profitable enough.
If You’re Reading This Because Your Plan Just Got Canceled
Don’t panic, but don’t wait either. Your guaranteed-issue window is real but limited. Call or text me at (623) 742-3878 (Arizona) or (910) 760-2124 (North & South Carolina) and let’s talk through what you actually qualify for right now. There’s no cost for the conversation, and I’ll tell you plainly whether a Medigap plan is a good fit for your situation — including when it isn’t.
Source: Meiselbach MK, Lavallee M, Xu J, Polsky D. “Forced Disenrollments Among Medicare Advantage Beneficiaries Following 2026 Plan Exits.” JAMA, February 18, 2026. Johns Hopkins Bloomberg School of Public Health.
Andy Orlikoff • NPN #7558435 • Licensed in Arizona, North Carolina & South Carolina
Verify this license at nipr.com Follow us on Facebook
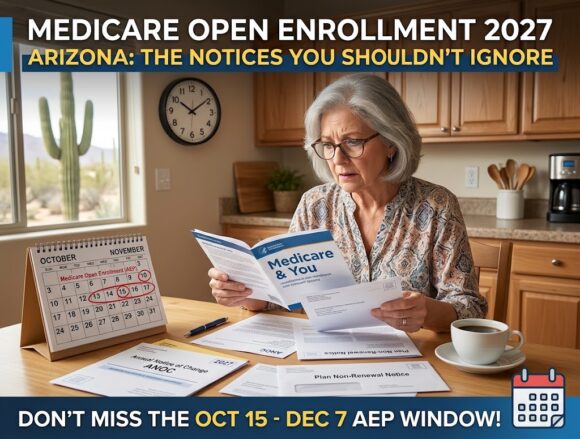 Medicare Open Enrollment 2027 Arizona officially opens October 15 and runs through December 7 — seven weeks to review your coverage and make changes for next year. But the window itself isn’t the hard part; the hard part is the stack of notices that show up beforehand, which most people skim past without realizing what each one is actually telling them.
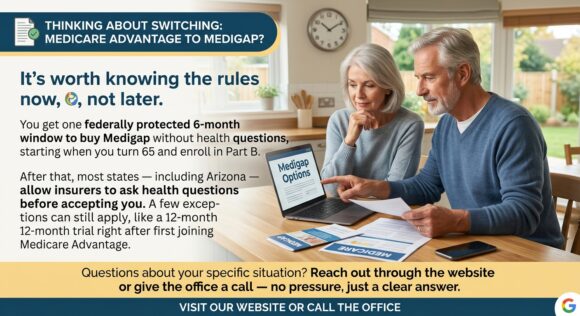 Choosing Medicare Advantage at 65 feels like a low-risk decision, especially with a low or zero monthly premium. The catch tends to show up years later: going from Medicare Advantage to Medigap can be much harder than getting into Medicare Advantage ever was. That’s worth knowing this fall, with Medicare’s Annual Election Period running October 15 through December 7.