Medicare changes 2027 Arizona seniors need to know about are here — 2027 brings some of the bigger shifts we’ve seen in a while — most of them affecting your wallet directly. Here’s what’s changing and what it means if you’re a Medicare beneficiary in Surprise, Sun City, Sun City West, or anywhere in the West Valley.
Part D costs are going up
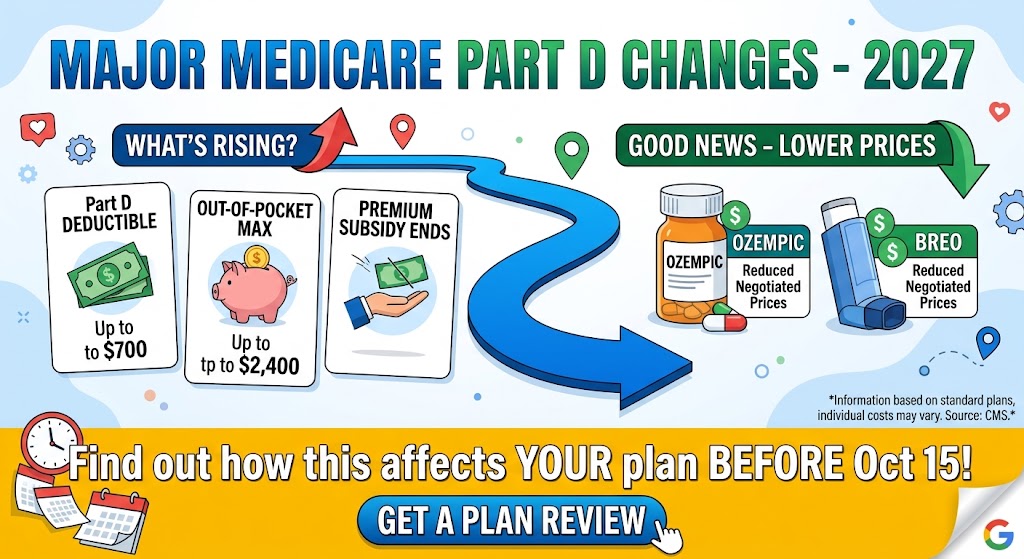
Two numbers matter here. The Part D deductible rises to $700 in 2027, up from $615 this year. And the maximum you’ll pay out of pocket for prescription drugs climbs to $2,400, up from $2,100. On top of that, a temporary subsidy that’s been softening Part D premiums by around $16 a month is set to expire, since the program funding it hasn’t been extended into 2027.
Fewer stand-alone Part D plans to choose from
If you’ve noticed your drug plan options shrinking, you’re not imagining it. Stand-alone Part D plans have dropped from around 30 options five years ago to about 11 heading into 2026 — and that trend is expected to continue. Fewer choices makes comparing what’s left even more important.
Some good news: lower prices on negotiated drugs
Medicare’s drug price negotiation program adds new savings for 2027, including notable reductions on widely used medications — Ozempic and Wegovy drop to roughly $274 (down from $959), and Breo Ellipta drops to about $67 (down from $397). If you take any of the newly negotiated drugs, this is worth checking against your current plan’s pricing.
Telehealth flexibility sticks around through 2027
Extended telehealth access, which many Medicare beneficiaries have relied on since the pandemic, has been extended through December 31, 2027, giving more time to see doctors remotely when an in-person visit isn’t necessary.
Medicare Changes 2027 Arizona: What This Means for Your Annual Enrollment Period
None of these changes take effect automatically in a way that protects you — they’re reasons to actually look at your coverage during this year’s Medicare Annual Enrollment Period, October 15 through December 7, rather than letting your plan auto-renew. A plan that made sense in 2026 may cost meaningfully more in 2027, or a competing plan may now price better for your specific medications.
Ready to see how these changes affect your specific plan? Call (623) 742-3878 for a free, no-pressure review before AEP opens. As an independent Arizona health insurance broker, I can also show you how a Medicare Supplement plan compares with staying on Medicare Advantage.
This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Please review your Annual Notice of Change (ANOC) letter for details specific to your current plan.
Staying on top of Medicare changes 2027 Arizona seniors are facing now can save real money and hassle later. If you want help sorting through your options, give us a call.
Every fall, Medicare’s Annual Enrollment Period (AEP) gives you a window to make changes to your coverage for the year ahead. This year, that window runs from October 15 through December 7, 2026. Any changes you make take effect January 1, 2027. Here’s what the Medicare Annual Enrollment Period Arizona season means for you this fall.
If you’re one of the many Medicare beneficiaries here in the West Valley — Surprise, Sun City, Sun City West, Peoria, and the surrounding communities — this is worth a spot on your calendar even if you’re happy with your current plan. Here’s why, and what you can actually do during this period.
What You Can Change During the Medicare Annual Enrollment Period Arizona
During the Annual Enrollment Period, you can switch from Original Medicare to a Medicare Advantage plan, or vice versa; move from one Medicare Advantage plan to another; change your Medicare Part D prescription drug plan; or enroll in a Part D plan for the first time if you didn’t sign up when you were first eligible (late enrollment penalties may apply).
One thing AEP does not cover: Medigap (Medicare Supplement) plans. Those have their own enrollment rules and typically require medical underwriting outside of your initial enrollment window.
Why review your plan even if nothing feels “wrong”
Plans change every year — provider networks, drug formularies, premiums, and extra benefits can all shift from one year to the next, even if you don’t touch a thing. A plan that was the best fit for you last January isn’t guaranteed to still be the best fit this January. A quick annual review is the only way to know for sure.
What working with an independent broker looks like
As an independent broker, I’m not tied to a single insurance company, which means the goal of our conversation is finding what actually fits your situation — not steering you toward one carrier’s product. A brief intake call to understand your current coverage, doctors, and prescriptions. Independent research across multiple carriers on your behalf. A clear, comprehensive quote emailed to you — no pressure, no obligation. You decide when (or whether) you’re ready to move forward, at your own pace.
Get Ahead of the Medicare Annual Enrollment Period Arizona Rush
AEP is a busy six weeks for everyone in this business. Reaching out before October 15 — rather than in the middle of it — usually means a more relaxed, unhurried conversation and more time to compare options carefully.
Ready to review your coverage before AEP begins? Call (623) 742-3878 or reach out through the contact form on this site, and let’s make sure your plan still fits.
This article is for general educational purposes and is not a comparison of specific plans or an endorsement by Medicare or any government agency. Please review your Annual Notice of Change (ANOC) letter for details specific to your current plan.
Medicare Part D 2027: Premiums Are Set to Rise — Here’s What Changed
Medicare Part D 2027 is shaping up differently than recent years. If you’re on a standalone Part D drug plan, there’s a real change coming worth knowing about before Open Enrollment starts this fall.
In late July 2026, the Centers for Medicare and Medicaid Services ended a program called the Part D Premium Stabilization Demonstration. That subsidy has been quietly keeping drug plan premiums low since 2025, holding the average monthly cost under $40. Without it, one federal watchdog report estimated premiums would have climbed from around $43 to about $81 a month. Now that the subsidy is gone, most experts expect standalone Part D premiums to go up for a lot of people in the new plan year — though nobody can say by exactly how much yet, since plan-specific pricing hasn’t been released.
I want to be upfront: I don’t sell standalone Part D plans, so this isn’t a pitch. But I talk to a lot of people every year who assume their Medicare coverage just renews itself the same way, year after year, and this is exactly the kind of change that makes assuming a bad idea.
What Actually Happens Next
Your Part D carrier will send you an Annual Notice of Change (ANOC) this fall. That letter spells out exactly what’s changing about your specific plan — premium, deductible, drug formulary, all of it. Don’t let it sit in a pile of mail.
Then you’ve got a real window to act. Medicare Open Enrollment runs October 15 through December 7. That’s your chance to compare Part D plans, switch if your current one got more expensive, or just confirm what you have still makes sense heading into Medicare Part D 2027.
While You’re Looking, Look at the Whole Picture
Medicare Part D 2027 pricing changes are a good excuse to actually sit down and look at your full Medicare setup, not just the drug plan. That includes your Medicare Supplement coverage — is it still the right fit, still priced competitively, still covering what you need? A lot of people haven’t checked in years.
If you want a second set of eyes on any of it — your Part D options, your Supplement plan, or just want someone to walk through what Open Enrollment actually means for your situation — give me a call or visit the website. No pressure, no call center, just a real conversation about what makes sense for you.
Here’s something most people don’t realize: you can switch Medicare Supplement plans in Arizona almost any month of the year — you’re not locked in. But “you can apply” and “you’ll get approved at a good rate” are two very different things, and the difference comes down to timing and your health. Let me walk you through how it actually works, because the rules aren’t what most people assume.
You Can Switch Medicare Supplement Plans in Arizona Anytime
Unlike Medicare Advantage, which locks you into set enrollment periods, Medigap plans have no annual “open enrollment” for switching. You can submit an application to change carriers or plans in January, July, or any month you like.
The catch is that outside of your protected windows, switching usually means going through medical underwriting — the insurance company reviews your health history and can charge you more, add exclusions, or decline you outright.
The One Window Where Health Doesn’t Matter
There’s a golden period when you can buy or switch to almost any Medigap plan with no medical underwriting at all: your Medigap Open Enrollment Period. This is the six-month window that starts the month you’re 65 or older and enrolled in Medicare Part B. During those six months, carriers must sell you a policy at their best rate regardless of your health.
If you’re in that window right now, this is the single best time to get the coverage you want. Miss it, and the rules change — which is exactly why timing matters so much.
Guaranteed Issue Rights: Switching Without Underwriting
Even outside that first six months, certain life events give you guaranteed issue rights — the right to buy specific Medigap plans without underwriting. These situations include:
Losing employer or group coverage — when the employer-sponsored, COBRA, or retiree coverage that pays after Medicare comes to an end.
Your Medicare Advantage plan leaving — if your MA plan discontinues in your area, shrinks its service area, or its contract terminates.
Trial rights — if you tried Medicare Advantage when you first became eligible (or dropped a Medigap policy to try MA) and switch back to Original Medicare within 12 months.
Your Medigap carrier failing — if your insurer goes bankrupt, ends coverage through no fault of yours, or misled you.
Moving out of your plan’s service area — for an MA or Medicare SELECT plan.
This is where a lot of Arizona retirees — and younger beneficiaries — leave money on the table. They assume they’re stuck, when a recent change in their situation actually opened a no-underwriting door. But that door closes fast: you generally have no more than 63 days after your prior coverage ends to use a guaranteed-issue right. In many cases you can even apply up to 60 days before the coverage ends, so acting early is smart.
One important note for Arizona specifically: unlike some states, Arizona does not offer an additional guaranteed-issue protection for under-65 Medicare beneficiaries who qualify by disability. If that’s your situation, it’s worth a call before you assume a switch is straightforward — your options and timing will look different, and I can walk you through what’s actually available.
Why People Switch in the First Place
The most common reason isn’t dissatisfaction with coverage — since all Medigap plans of the same letter are standardized by law, a Plan G from one carrier covers exactly what a Plan G from another does. The real driver is price. Carriers raise rates over time, and the company that was cheapest when you enrolled may not be cheapest three years later.
Because the benefits are identical, moving to a lower-priced carrier for the same plan letter is often pure savings — you keep the exact coverage and pay less for it.
What Switching Actually Involves
The process is more straightforward than people fear:
You apply with the new carrier and go through underwriting (unless you’re in a protected window).
You don’t cancel your old policy until the new one is approved and active — never leave yourself with a gap.
Once the new plan is confirmed, you cancel the old one, and you’re done.
The mistake I see most often is people canceling first out of eagerness, then getting declined by the new carrier and scrambling. Approval first, always.
How I Help Arizona Clients Decide
This is exactly the kind of situation where an independent broker earns their keep. I’m contracted with multiple carriers across Arizona, so I can check whether a switch actually saves you money for the same standardized coverage — and whether your timing puts you in a protected window or means underwriting. There’s no cost to you, and I never push a switch that doesn’t benefit you.
If you’re wondering whether you’re overpaying, or whether a recent life change opened a no-underwriting window, it’s worth a quick conversation before that window closes.
If you buy your own health insurance in Arizona, one question matters more than almost any other: do you qualify for an ACA subsidy? The answer decides whether a plan costs you a few hundred dollars a month or almost nothing — and a lot of people leave real money on the table because they assume they earn too much, or too little, to qualify. Let me clear up how it actually works.
What an ACA Subsidy in Arizona Actually Is
The subsidy — officially the premium tax credit — is money the federal government applies directly to your monthly health insurance premium when you buy a plan through the Marketplace. It lowers what you pay out of pocket each month. The amount depends mostly on your household income and household size, measured against the federal poverty level.
Here’s the part people miss: it’s not a rebate you wait for at tax time. It’s applied up front, every month, so your premium is lower from day one.
Eligibility hinges on your estimated annual household income for the coverage year, your family size, and whether you have access to affordable coverage elsewhere (like an employer plan). Because it’s based on estimated income, self-employed people and those with variable earnings have real flexibility — and real reason to get the estimate right.
Who Qualifies — and the Myth That Costs People Money
The Two Ways People Get It Wrong
I see two mistakes constantly. First, people overestimate their income out of caution and miss subsidies they’d have qualified for. Second, they underestimate and owe money back at tax time. Getting the income estimate accurate is where a broker earns their keep — it’s the difference between a pleasant surprise and an unpleasant one.
How the 2026 Rules Affect What You Pay
The enhanced premium tax credits that had removed the income cap expired at the end of 2025. For 2026, the subsidy cliff is back: the credit slides on a sliding scale up to 400% of the federal poverty level, then stops completely. That cutoff works out to roughly $62,600 for a single person and $128,600 for a family of four — earn a dollar over and the credit drops to zero. The safest move is to have your actual numbers run against this year’s brackets rather than relying on last year’s assumptions or a general rule of thumb.
Arizona Uses the Federal Marketplace
Arizona doesn’t run its own state exchange — residents enroll through the federal Marketplace at Healthcare.gov. That means the same federal subsidy rules apply here as in most states, but the plans available, their networks, and their prices are specific to Arizona and even to your county.
Two things worth knowing if you’re shopping for 2026 or 2027 coverage in Arizona specifically: Aetna exited the state’s individual market and Blue Cross Blue Shield of Arizona dropped its PPO products, which means every on-exchange plan for 2026 is HMO only — if you want PPO flexibility, you’ll need to look off-exchange. And Cigna announced in April 2026 that it’s leaving the ACA Marketplace nationwide, including Arizona, starting with the 2027 plan year. If you’re currently on a Cigna Marketplace plan, your coverage ends December 31, 2026, and you’ll need to pick a new plan for January 1.
When You Can Enroll
Most people enroll during the annual Open Enrollment Period. But if you’ve had a qualifying life event — losing other coverage, moving, marriage, a new baby, a change in income — you may qualify for a Special Enrollment Period and can enroll outside that window. Don’t assume you’ve missed your chance; it’s worth checking.
How I Help Arizona Families Get This Right
This is exactly where an independent broker saves you money and headaches. I’ll run your actual household numbers against the current subsidy brackets, show you what you truly qualify for, and compare the Arizona plans available in your county — not a generic quote. There’s no cost to you, and if a subsidized Marketplace plan is your best math, I’ll tell you; if something else fits better, I’ll tell you that too.